Paul Cavey

Paul Cavey

East Asia Today

East Asia Today

Japan's Q2 flow of funds data give an update on several underlying aspects of the economy. Some charts on Korea's 2027 budget. And also, a couple of pieces on Taiwan, covering the CBC's on-hold decision today, and why I thought rates would (should) be higher.

2 min read

Taiwan – on hold

Taiwan – on hold

Consensus was right, and the CBC didn't change rates today. The vote wasn't unanimous, with two members voting for a hike. However, some of the property measures were loosened. To me, this suggests that policy is too loose, and thus that the gradual warming up of inflation will continue.

1 min read

Japan – FOF trends

Japan – FOF trends

Q2 flow of funds: 1) firms remain net savers; 2) the fiscal deficit is under 2% of GDP, and government assets continue to rise; 3) GPIF, foreigners and households are absorbing JGB supply as the BOJ steps back; 4) household equity holdings are up sharply, but mainly because of valuations.

3 min read

Taiwan – the fall in real rates

Taiwan – the fall in real rates

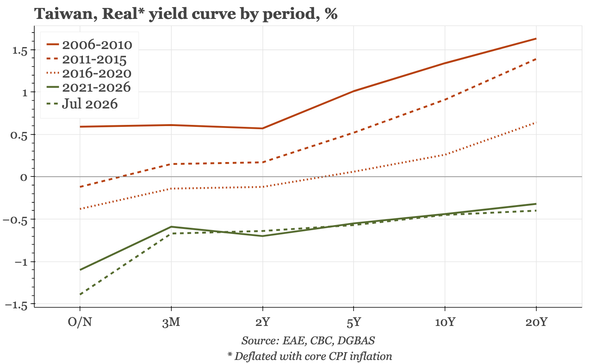
I expect the CBC to hike. That was also my view 3M ago, and then I was wrong, and the strong consensus is that I'll be wrong now too. Underlying my view is that the CBC can't be confident inflation has peaked. Instead, with real rates negative and the TWD weak, price pressures are likely to persist.

6 min read

East Asia Today

East Asia Today

Machine orders and trade data for Japan confirm an upturn in the manufacturing sector. China's fx settlement data yesterday show August was another month of decent capital inflows. The renewed upturn in property prices in Taiwan is continuing.

2 min read

East Asia Today

East Asia Today

Lot of data released in China, none of which show any change in the story. Japan's service growth remains strong, but manufacturing output is now also rising too. August terms of trade data in Korea indicate yet faster nominal GDP growth in Q3. Outbound FDI in Taiwan remains strong.

3 min read

China – still no break

China – still no break

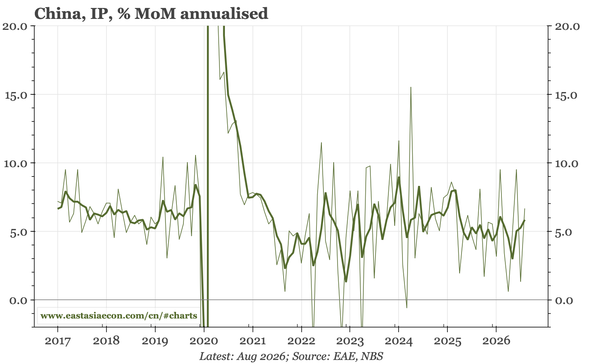
Domestic demand remains soft, with no break in the property market collapse. But helped by exports, IP is growing near 6% saar, which keeps the GDP growth target for this year in reach. So I doubt much changes in terms of policy, but the emerging weakness in services is something to be monitoring.

3 min read

East Asia Today

East Asia Today

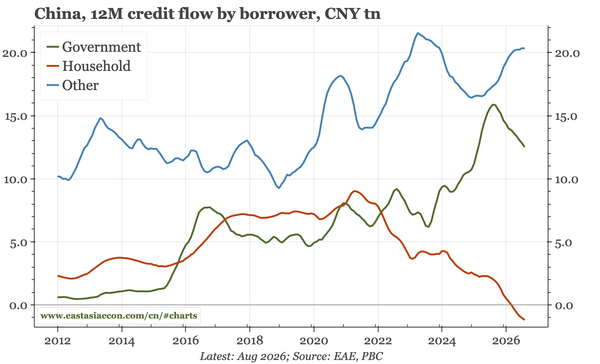
A longer note today catching up on last week's interesting Q2 GDP release in Korea. Also, charts covering today's release of August monetary data in China, and July wages in Taiwan.

3 min read

Korea – the rising tide

Korea – the rising tide

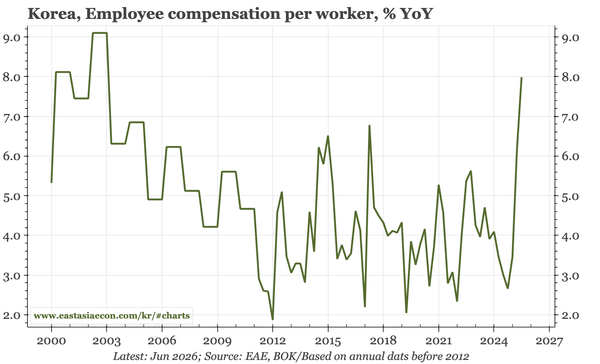
Last week's GDP data showed nominal growth of over 25% YoY in Q2. Most of that was in the form of corporate profits, but employee compensation still rose 8% YoY. With the government planning growth in fiscal spending of 12% in 2027, there are more signs of the IT sector lifting the broader economy.

4 min read

East Asia Today

East Asia Today

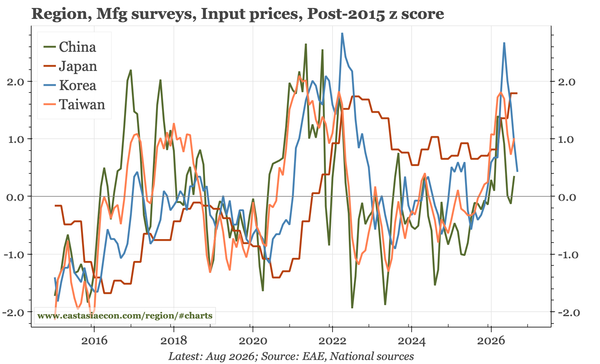
Korean BOP data for August, an update on upstream prices in China, which have been stronger than I had been expecting, and PBC liquidity operations through August. Foreign exchange reserves in Taiwan rebounded in August. I am away next week, so the next update will be Monday 14th September.

3 min read

Korea – from selling to buying

Korea – from selling to buying

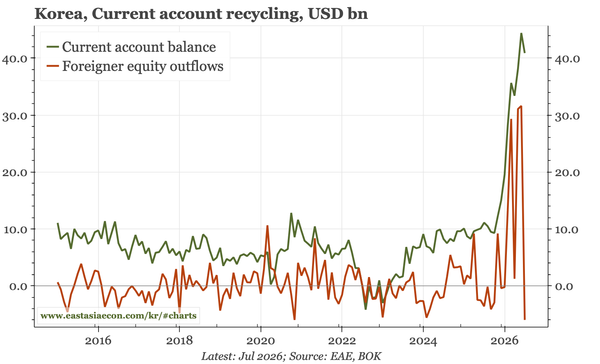
Today's BOP data show that after selling more than USD30bn of domestic equities in June, foreigners purchased USD6bn in July. That swing goes a long way to explain the sudden appreciation of the KRW. That should be able to continue, given CA surplus of over 20% of GDP, strong economy, and BOK hikes.

2 min read