
Subscribers Only

Last week, next week
China's nominal cycle looks to be slowing again. The rest of the region remains strong, but confidence that this strength can be retained is fraying, and will likely remain under pressure, especially if concerns over the data centre build-out and energy prices worsen again after the mid-terms.
Subscribers Only

China – px firm, construction not
Headline official PMIs continue to closely hug the 50 threshold. I am not sure that tells us much about the economy. But two components of the PMI are useful. The ongoing slump in construction indicates no property revival. Price indicators show PPI still strong, but warn of some weakening in CPI.
Subscribers Only

China – enough for 2026, but not 2027
From the perspective of a government that wants to meet a 2026 growth target without having to shift policy, the September data are encouraging. But the 2027 outlook for the domestic economy is looking more challenging. That will become more visible if global demand and price trends change.
Subscribers Only

China – squeeze, shock or shortfall
A chart pack focused on China's trade: the China Squeeze isn't so severe; the China Shock is, but is likely to intensify further; as important as both is a shortfall in imports, which is broad-based, and worsening. That reflects weak demand, which Beijing still shows no urgency in addressing.
Subscribers Only

China – external boost
That external factors continue to be the driving force of China's cycle dynamics was once again evident in the strength of both exports and PPI inflation in September. The combination puts a floor under overall nominal growth, and makes it unlikely that domestic policy becomes more aggressive.
Subscribers Only
China – mixed PMIs, incremental policy
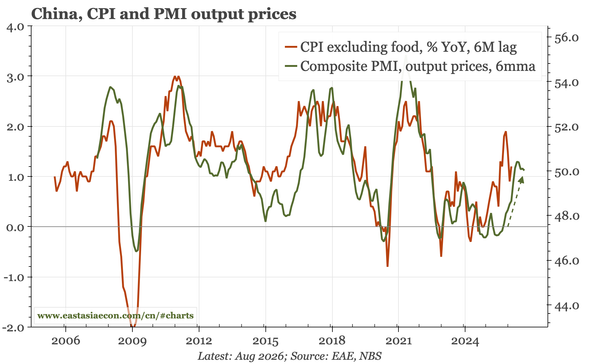
The manufacturing PMIs remain mixed. The S&P version is much stronger. And while weak in level terms, prices in the official versions are strong. This is the context for the latest, incremental, policy measures: from Beijing's perspective, conditions just aren't bad enough to warrant a new approach.
Subscribers Only
China – still no break
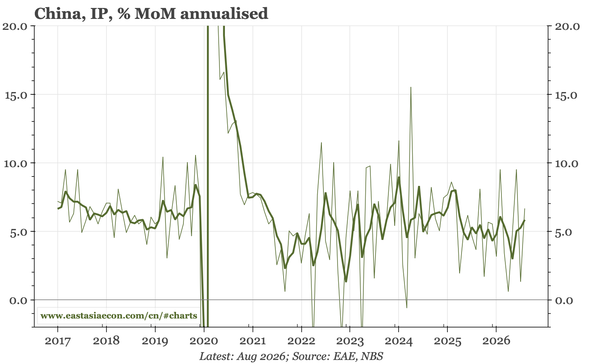
Domestic demand remains soft, with no break in the property market collapse. But helped by exports, IP is growing near 6% saar, which keeps the GDP growth target for this year in reach. So I doubt much changes in terms of policy, but the emerging weakness in services is something to be monitoring.
Subscribers Only
China – no change
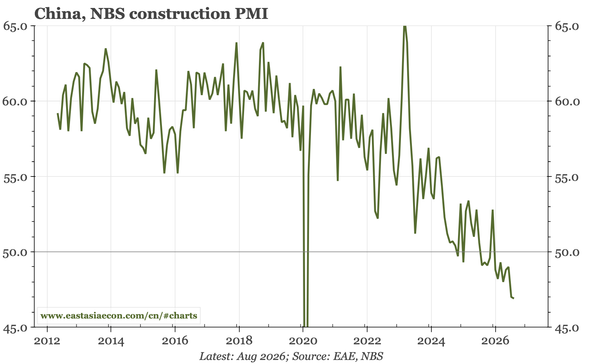
The PMIs continue to show no economic cycle. Construction activity continues to drop, but the manufacturing PMI continues to hover around the 50 mark. Input prices have rebounded again, so this year's recovery in PPI isn't ending just yet. None of these changes point to a shift in policy.
Subscribers Only
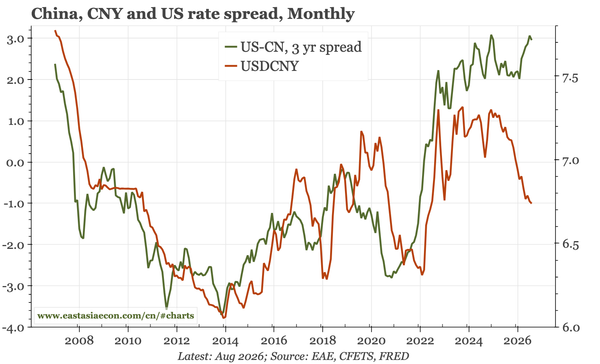
China – cycle concerns v the CNY
I am still totally convinced that cycle dynamics today are that different from 6M ago. But that property still hasn't found a floor is a concern, and it would now be less of a surprise if monetary easing starts again. For me, the interesting question is whether that has implications for the CNY.