
Subscribers Only

Last week, next week
The sustainability of the AI cycle is critical for the region. If it ends, rates will likely be lower, but currencies not necessarily weaker. Otherwise, my themes are: China – tougher 2027; Japan – flatter curve; Korea – macro spillover; Taiwan – market spillover.
Subscribers Only
Last week, next week
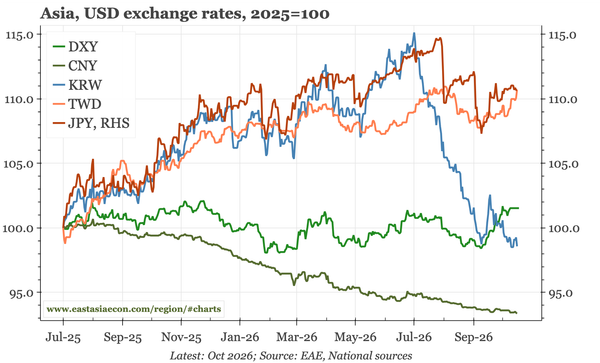
With regional macro dependent on continuation of the US AI build-out, the equity sell-off last week matters. That said, there are still complications: TSMC still sounds very bullish, and while for bad economies, it isn't clear that an end of the AI cycle would be so negative for currencies.
Subscribers Only

Last week, next week
I don't think the China-EU sectoral deal means a China-EU CNY deal is coming. The cycle continues to improve in Japan. Export momentum in Korea and Taiwan remain strong, with more signs of spillover into inflation in Taiwan. Links to all last week's research, as well as my latest podcast appearance.
Subscribers Only
Last week, next week
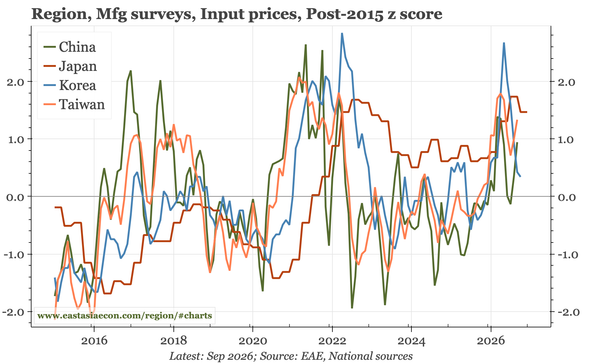
China's incremental policy is unlikely to move the cycle. Japan's nominal growth is strong enough to make the October BOJ meeting interesting. In Korea, the mainstream MPC view of one hike in the next 6M looks light. The revival in property sentiment in Taiwan is important given negative real rates.
Subscribers Only
Last week, next week
I am away the next few days, so this week's summary focuses on what appeared on the site in the last week. I am back on Monday 14th September.
Subscribers Only
Last week, next week
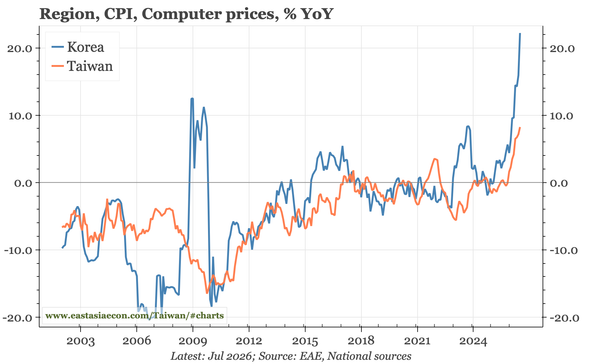
China macro is again a contrast between export strength and renewed deflationary pressure. Takaichi's sales tax cut doesn't look like the policy approach Bessent wants. For Korea, data an BOK analysis points to upside risks. In Taiwan, the key issue is lagged spillover from the 24-25 export boom.
Subscribers Only
Weekly: CMXT and JPY
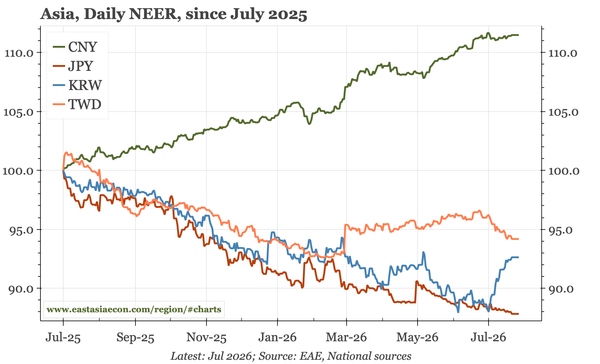
The two big events this week are China's CXMT listing and the Bank of Japan meeting. The first matters because the outlook for chip demand is such a dominant regional theme. The BOJ meeting is important because of rates in Japan, but also implications for the JPY and regional currencies.
Subscribers Only
Weekly
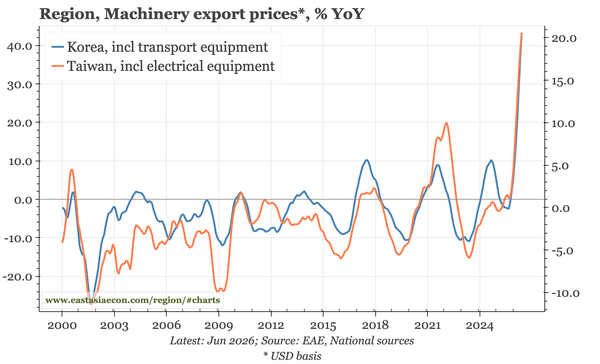
China's combination of recovering output, weak expenditure, and mixed monetary isn't great, but also doesn't suggest a big change in macro policy. I think it unlikely that Japan's bid for repatriation works without more BOJ normalisation. Korea and Taiwan cycles remain strong, implying rate hikes.
Public Post
Region – the upside risks to inflation
My latest video, discussing why inflation risks won't end even if the Iran War eventually does. The reasons: both cost-push and demand-pull from the semiconductor boom, dynamics that are being reinforced by the cheapness of currencies.