Taiwan – mixed export indicators
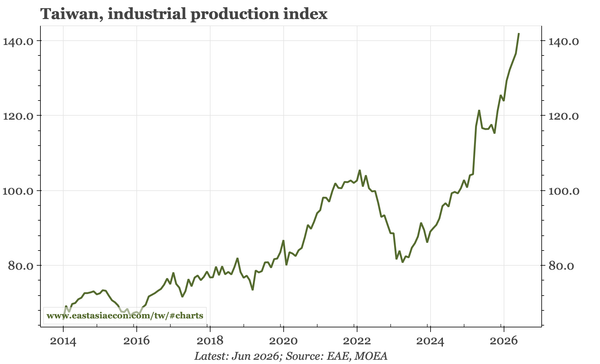
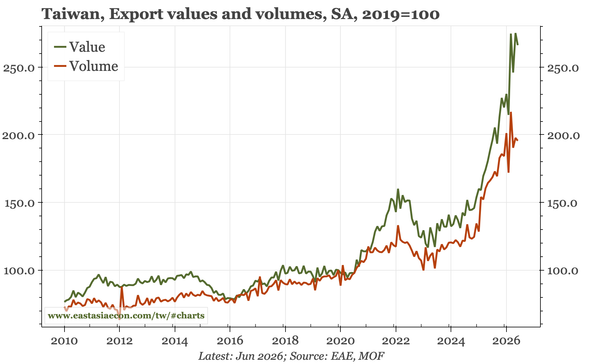
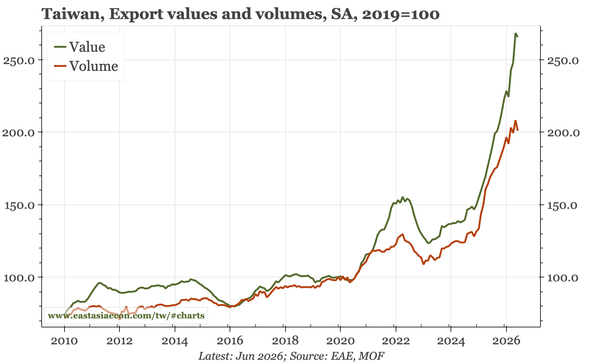
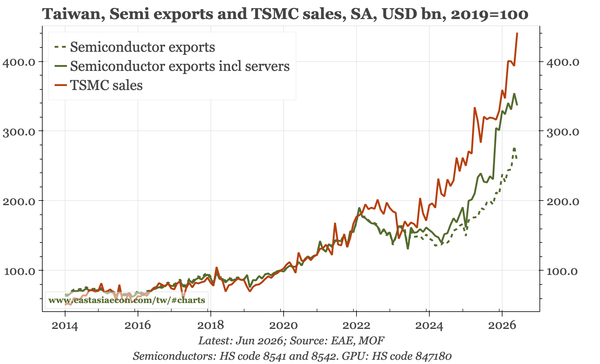
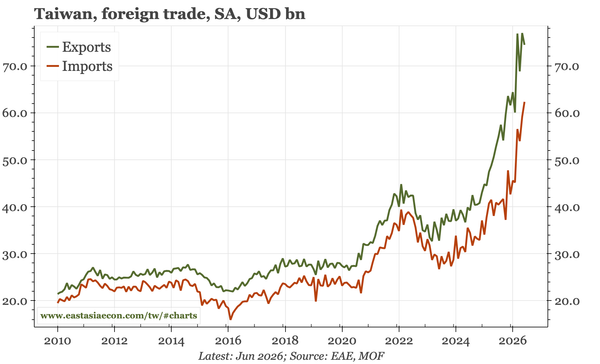
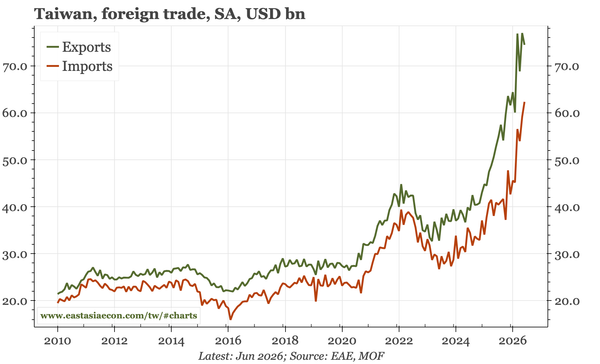
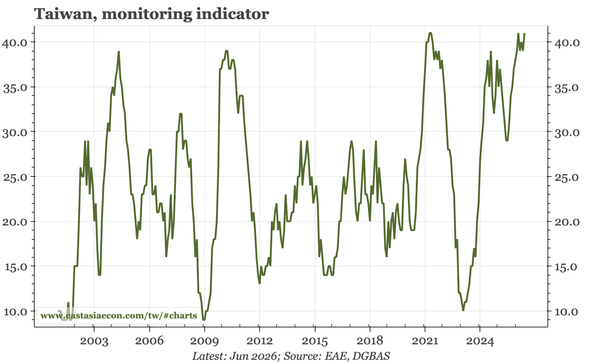
Taiwan's export indicators have become more mixed in recent weeks. On the one hand, reported exports in both value and volume terms have softened. On the other, TSMC sales and commentary have been strong, and today's export orders for June continued to rise, led by semiconductors.
Korea – 20-day exports up over 60%
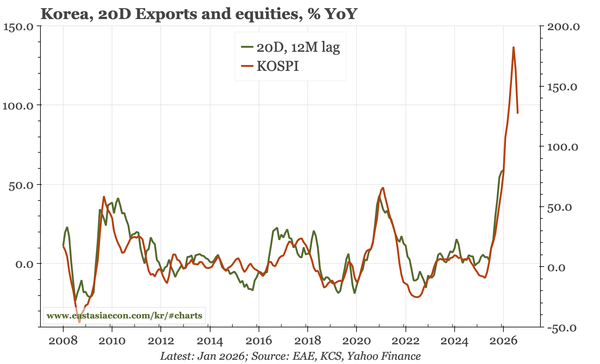
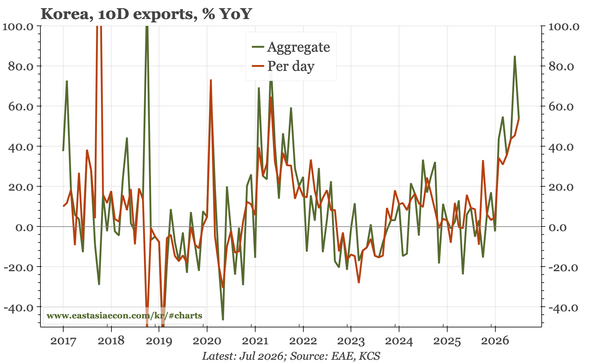
YoY growth in Korean exports in the first 20 days of July accelerated again to over 60% YoY. That was partly base effect, with the level of exports edging down. That softening was, however, only apparent in non-tech exports; the value of chip exports rose again, as did the trade surplus.
Taiwan – export volumes dip
Taiwan's export volumes dipped in June, and in Q2 as a whole were basically flat. Not being nearly as cyclical, Taiwan's semi export prices aren't rising nearly as quickly as in Korea, so the peaking of export volumes feeds into a peaking of export values.
China – consumption leads Q2 GDP
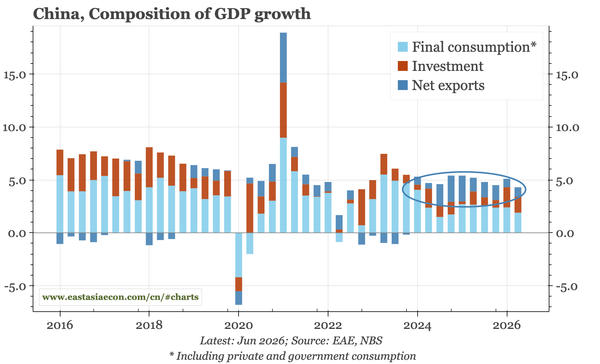
Today's release of detailed GDP data for Q2 showed the biggest contribution to growth came from consumption (1.9ppts), followed by investment (1.5ppts). That will be puzzling to many when retail sales in the quarter fell a bit, and fixed asset investment fell a lot.
Korea – positive terms of trade shock
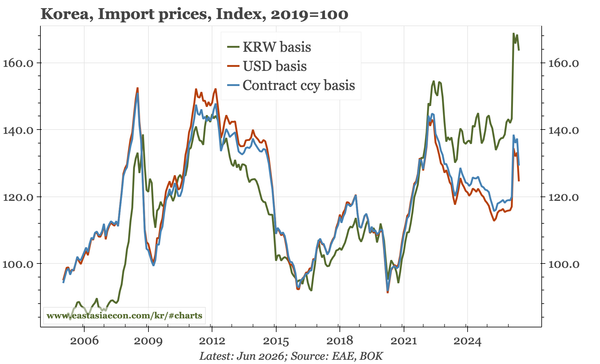
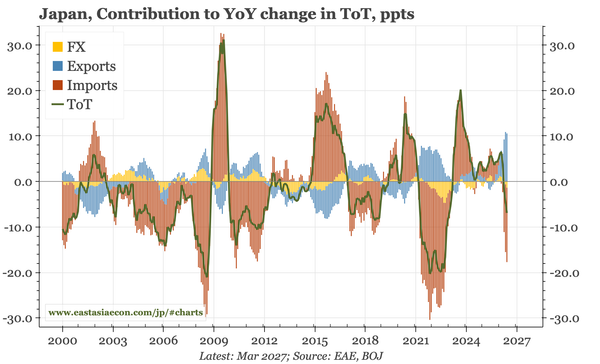
The extent of the positive terms of trade shock was visible in today's data for export and import prices for June. Import price inflation eased, but export prices rose almost 50% YoY. The improvement in the terms of trade of Q1 accelerated in Q2.
Japan – best momentum in several quarters
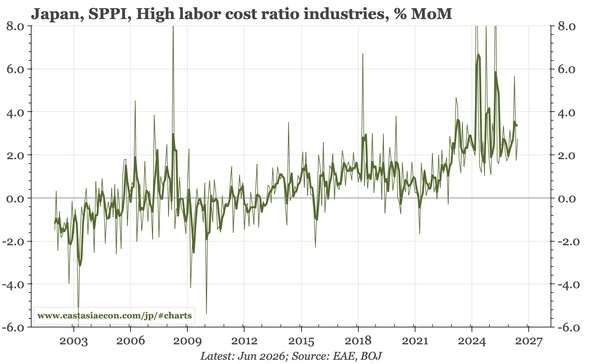
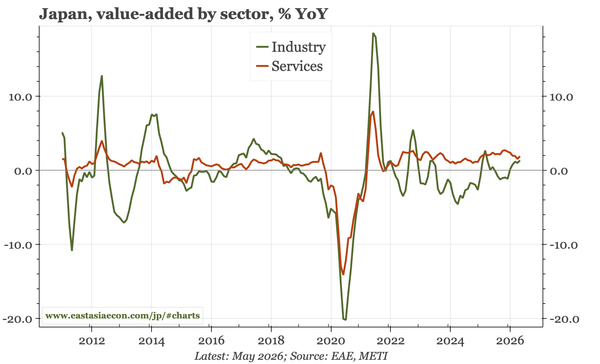
Momentum in Japan's economy is the best it has been in several quarters. Today's data for May showed services output strong once again. Goods output has also picked up this year, and the separate release today of machine orders data for May indicate the stronger growth sustaining.
Taiwan – exports look peaky
In level terms, headline USD exports in recent months, while remaining high, have started to look peaky. However, the slowdown hasn't yet appeared in volume data, and TSMC's sales for June that were released yesterday suggest the upcycle for export values may not be completely over either.
Taiwan – May wages delayed
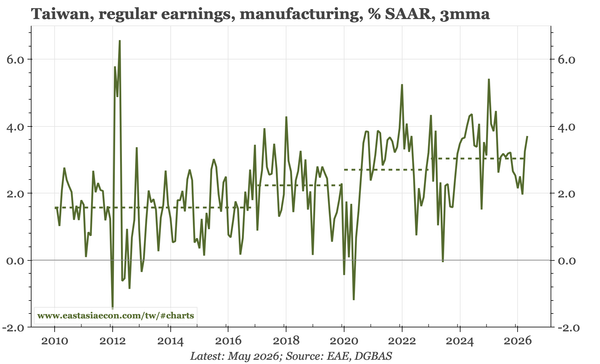
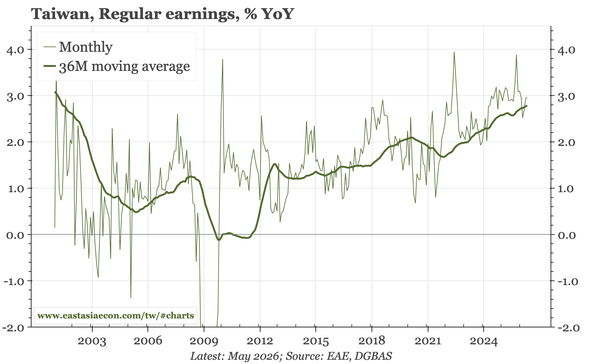
The May wage data were released Frifay, but by the evening the government's database still hadn't been updated. It has now, and the numbers show the gradual pick-up in wage growth is continuing. That is led by manufacturing at 3% annualised, but since 2023 services growth has also picked up to 2.7%.
Korea – noisy early-July trade
10D trade data tend to be noisy, and true to form, the message from today's release for the first third of July differs depending on which way the numbers are cut: headline YoY growth in exports slowed; the YoY change in workday-adjusted exports accelerated to 60%; and in level terms workday…
Taiwan – wage data delayed
Perhaps because offices in Taipei have been closed today due to a typhoon, the government's database hasn't yet been updated with today's wage data for May. The headlines suggest underlying wage growth is now near 3%, with momentum in both manufacturing and services picking up since 2024.
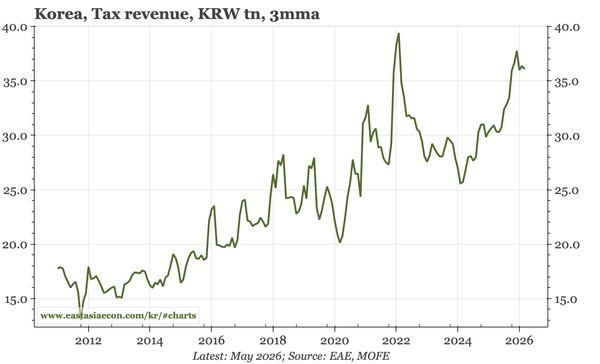
Korea – fiscal channel for the chip boom
Fiscal policy is one mechanism by which the big increase in national income produced by the semiconductor boom can lift the wider economy. Data today show that tax revenues rose more than 17% YoY in the first five months of this year. According to today's press release (machine translated):
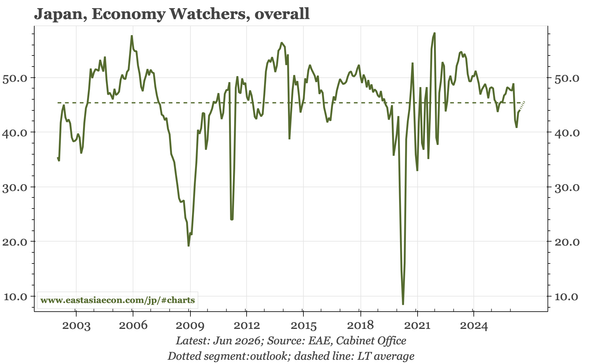
Japan – Economy Watchers recovery lags
The Economy Watchers survey improved in June, but the recovery was less than seen in other recent surveys. That was a surprise, and I'd expect more improvement in July. Cycle strength did continue to be seen in bank lending in June, which continued to rise.