Archive
East Asia Econ Paul Cavey

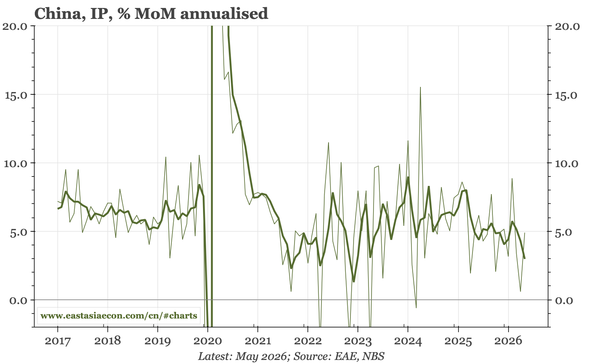
China – another month of weak data

China – another month of weak data

I have been arguing that the underlying economy has been stabilising, with prices bottoming out before the Iran war. But stabilisation is external-led, and today's data show the domestic cycle remains a mess. That will likely become a policy issue if IP doesn't stay at an annualised run-rate of 5%
3 min read

Korea – Shin's surer

Korea – Shin's surer

BOK governor Shin Hyun Song gave a speech on Friday to mark the 76th anniversary of the bank's founding. It was short, but worth highlighting, because he sounded more confident about the outlook, and downplayed the significance of uneven growth as a factor for monetary policy.

3 min read

Last week, next week

Last week, next week

Three themes: whether the weakness in the activity data releases of a month ago in China was noise; Japan, where one hike is unlikely to be enough to really change market conditions; and the semi super cycle, which should be having more impact on fx and rates (in Taiwan) than has yet been evident.

6 min read

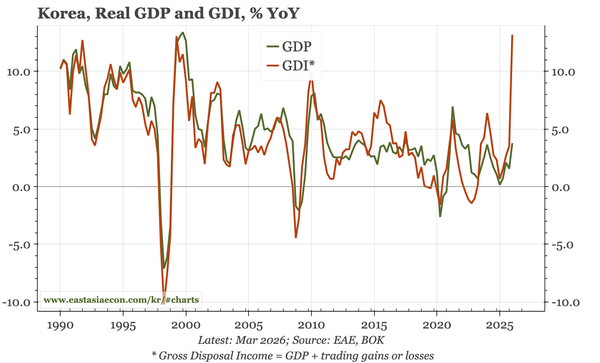
Korea – huge nominal growth

Korea – huge nominal growth

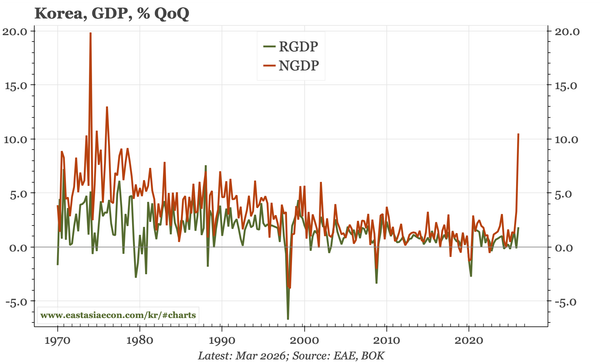
Korea is experiencing a large positive terms of trade. As that isn't being accompanied by any KRW appreciation, the result is enormous growth in KRW nominal indicators. Not all sectors are benefiting. But for monetary policy, the strength of nominal growth is impossible to ignore.

2 min read

Korea – not totally K-shaped

Korea – not totally K-shaped

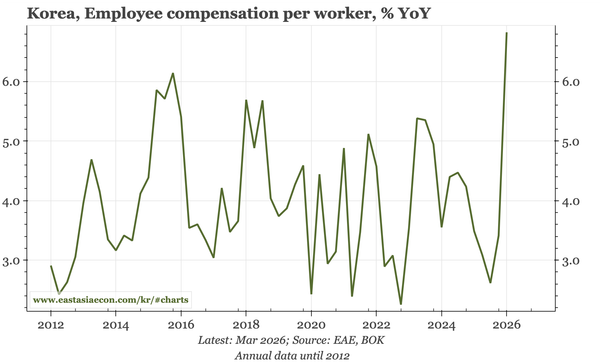
The corporate surplus is surging, and at first glance, that supports the idea that the semi-led cycle won't trickle down. However, while the labour share is falling, the rise in national incomes has been so strong that growth in labour compensation is accelerating. That should support spending.

2 min read

Japan – import prices up, but export prices too

Japan – import prices up, but export prices too

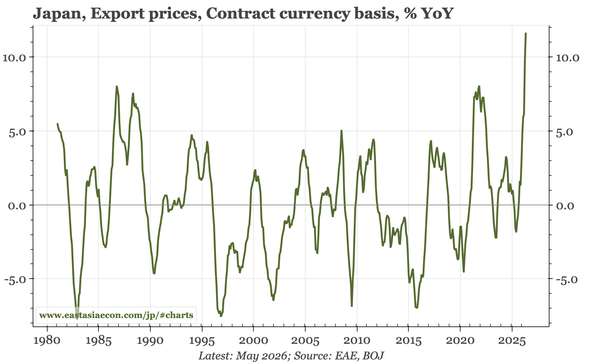
The renewed rise in import prices is certainly inflationary, especially when the level of prices remains elevated after the hikes of 2021-22. However, this time export prices are rising too, and while that isn't enough to prevent the ToT from falling, it does limit the damage to the domestic economy

2 min read

China – externally driven inflation

China – externally driven inflation

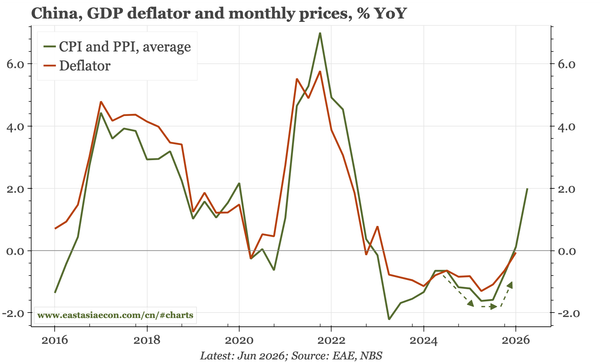
The rise in PPI that continued in May is of macro significance: it is pushing up industrial sector earnings, and the GDP deflator will likely turn positive in Q2. But it is difficult to find signs of domestically generated inflation that would suggest a real upturn in the economy.

2 min read

China – imports and exports strong in May

China – imports and exports strong in May

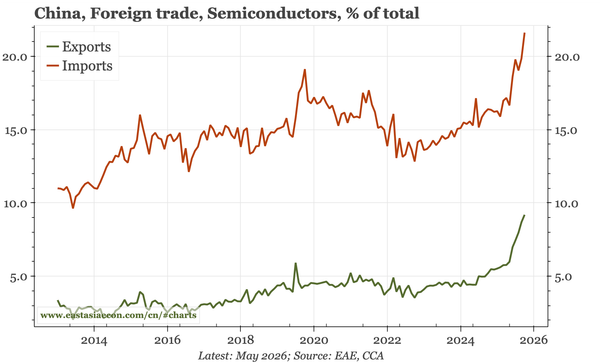
Chips rather than energy have been the bigger driver of trade patterns this year. That's true for exports and imports, though there are other drivers of both reaching record highs in May: autos for exports, ores and likely gold for imports. Despite the rise in imports, the trade surplus remains big.

2 min read

Japan – enough, if the BOJ decides it is

Japan – enough, if the BOJ decides it is

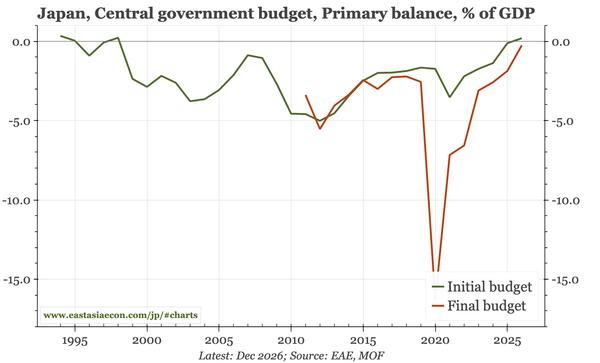
The narrowing budget deficit and widening BOP surplus likely won't move market opinion on either rates or fx. What is needed remains a more hawkish BOJ. Accelerating credit and wage growth push in that direction, though the wage data aren't great quality, and sentiment surveys are still weak.

4 min read

Last week, next week

Last week, next week

Events in Japan in the next couple of weeks will likely be critical for the region. If a combination of a strong US jobs report and equivocal BOJ meeting push $JPY through 160, KRW and TWD will likely be dragged higher too. The implication would be higher inflation, and more pressure for rate hikes.

6 min read

Taiwan – services inflation back at 2.5%

Taiwan – services inflation back at 2.5%

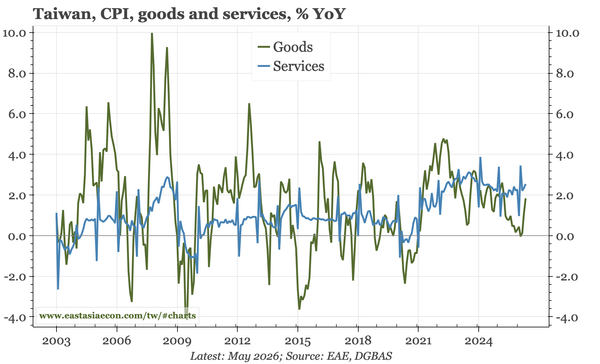
Services inflation averaged 0.7% in the 20 years before 2020. In the last five years it has been 2.3%, and is now rising again. Some of that reflects energy prices, with air fares rising 10% YoY in May. But there is also the backdrop of a strong economy, rising stockmarket and rising wage growth.

2 min read

Korea – the all-weather weakness of the KRW

Korea – the all-weather weakness of the KRW

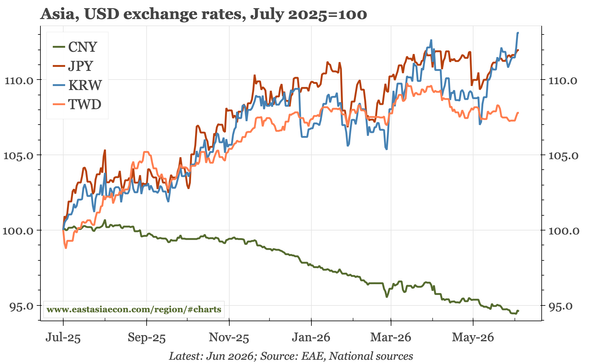
KRW weakness was blamed on USD strength, then CNY weakness, then JPY weakness. Flows have gone from NPS, to domestic retail, to foreigner institutional. These rationalisations feel a bit like moving the goalposts. But weak KRW does have implications, one likely being a more hawkish BOK.

3 min read

Region – three themes in auto

Region – three themes in auto

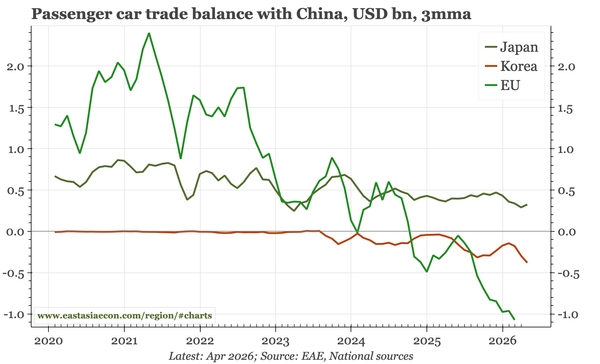
China's auto export surge has been less painful for Asia than for the EU. Japan's domestic market is more protected, and Korean exporters have little dependence on the China market. In third markets, exports have also held up, with tentative signs that China's exports are creating new demand.

4 min read

Japan – Ueda stresses inflation risks

Japan – Ueda stresses inflation risks

Some highlights from governor's speech today: his remarks about strong bank lending, higher prices being a bigger burden to firms than rising rates, the link between low policy rates and the rise in market yields, and the upside risks to prices now that the "deflationary mindset has been dispelled".

3 min read

Region – understanding Asia's chip cycle

Region – understanding Asia's chip cycle

My latest video, a discussion of everything you need to understand the macro implications of the huge chip cycle – what's driving it, why prices and volumes matter, the role of China, the growth and inflation consequences, and what it all means for markets.

1 min read

Korea – CPI still mainly energy

Korea – CPI still mainly energy

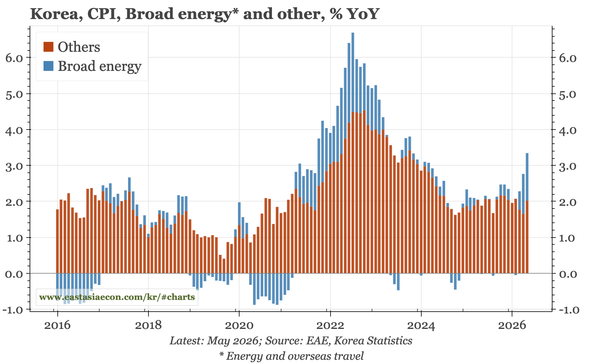
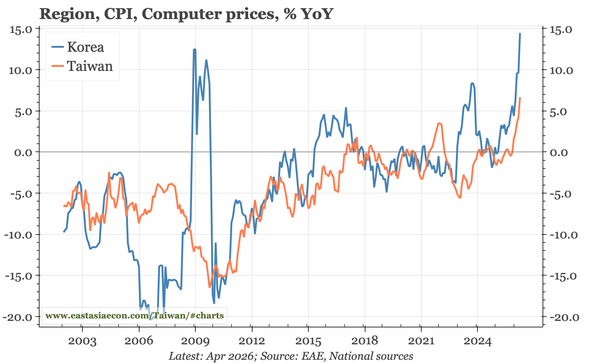
The rise in inflation is mainly about energy. But that headline inflation is now above 3% YoY – and private services over 4% – also reflects two other drivers: a high starting point, and the rise in chip prices that via cost-push is showing up in the CPI in higher prices for electronic devices.

2 min read

Last week, next week

Last week, next week

Four themes: broader inflation risks, for the region and world; feedthrough from exports to domestic demand; semi cycle rather than energy as the dominant dynamic; likelihood of monetary tigtening.

7 min read

China – no big change in PMIs

China – no big change in PMIs

In today's official data, headline PMIs for both manufacturing and services remain around 50. The details of the manufacturing PMI don't suggest much Middle East disruption. The run-up in prices that pre-dated Iran is, however, sustaining. On the other hand, employment remains weak.

2 min read

Taiwan – growth up, now inflation too

Taiwan – growth up, now inflation too

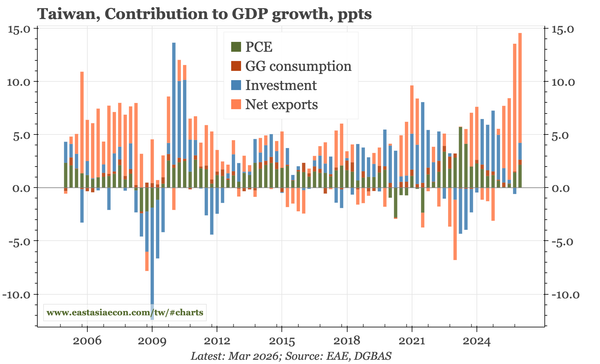
Today's Q1 GDP data show the economy growing more quickly than any time in over 40 years. The government thinks that continues: in the forecast, downside risk from Iran isn't mentioned, but trickle down from semi to the real economy is. CPI was also revised up, even if it remains (just) below 2%.

3 min read

Korea – mixed month-end data

Korea – mixed month-end data

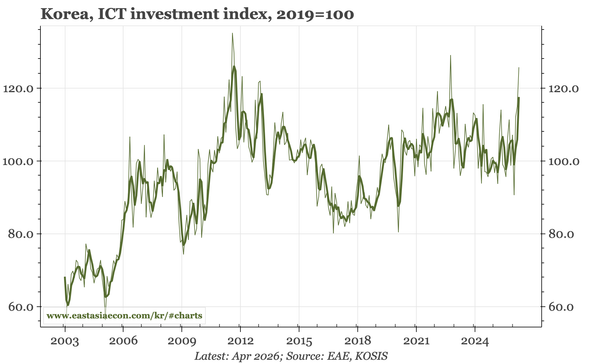
Two of the key issues for the economy are whether the chip boom trickles down, and what damage the Iran war will cause. April data show a bit of both. ICT capex rose for the third month, and there were more signs of a floor in the labour market. Overall output fell, but remained above the Q1 average

2 min read

Region – inflation risks

Region – inflation risks

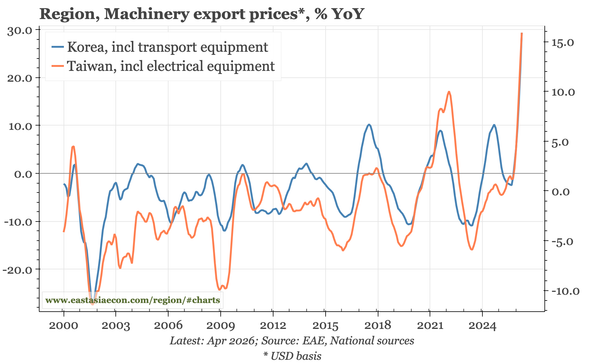
Big oil price hikes matter, but have been seen before. It is the rise in chip prices, and the gap between surging trade surpluses and weak currencies, that is unprecedented. If fx markets don't price these developments, central banks and fixed income will have to do so instead.

5 min read

Korea – everything but a hike

Korea – everything but a hike

The BOK didn't change rates today, but signalled that despite continued uncertainty, higher rates are coming. The pace will depend on dynamics in the energy and chip markets. I would also be watching for how core CPI performs against the BOK's modest forecast of 2.4%

2 min read

China – underlying profits a bit better

China – underlying profits a bit better

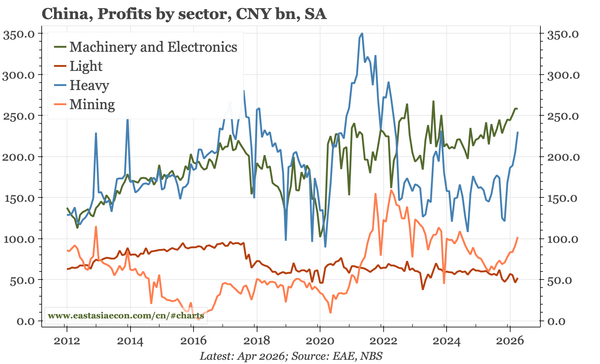
The bounce in headline profits in April was largely base effect, but there are signs of underlying improvement: revenues have started to rise, the increase in PPI is boosting profits in heavy industry, and hasn't yet derailed the post-2024 increase in total downstream manufacturing earnings.

3 min read

Korea – ticking four boxes for a hike

Korea – ticking four boxes for a hike

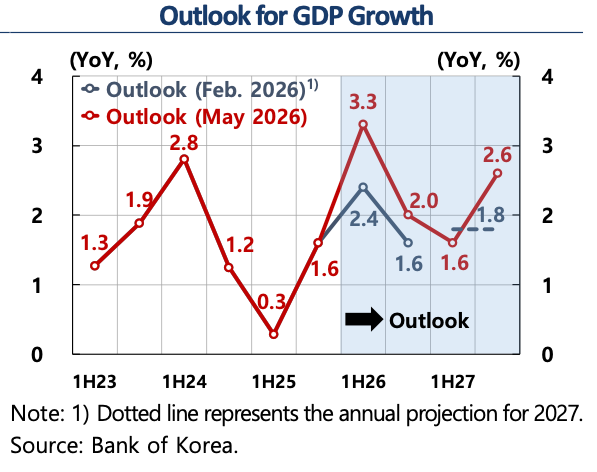
The BOK's main considerations for policy are growth, inflation, KRW and housing. Three were already pointing to hikes, and tomorrow the bank is likely to raise expected growth above potential too. That makes a rate hike likely. The risk is it still just a bit too early.

7 min read

China – consequences of the semi surge

China – consequences of the semi surge

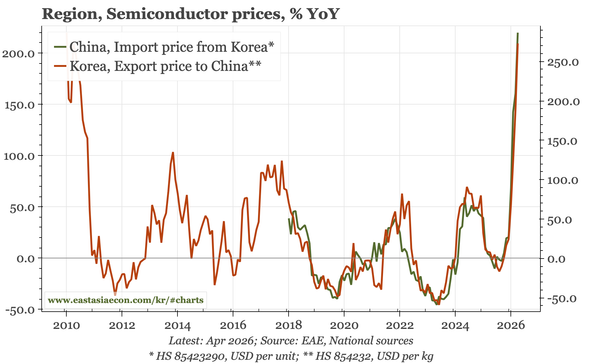
The surge in semiconductor exports that is such an import theme across the region is also an important dynamic in China. But in China, the semiconductor trade has broader implications: for the trade surplus, import demand, the export outlook, and inflation, both in the region and ROW.

5 min read