Archive
East Asia Econ Paul Cavey

Korea – BOK remains cautious

Korea – BOK remains cautious

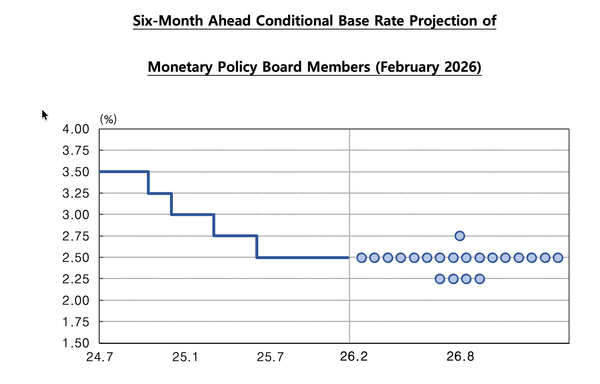
The tone from today's BOK meeting was cautious. The new rate dot plot suggests that at the margin risks for policy are still weighted towards loosening, the upgrade to the GDP growth forecast was only 0.2ppts, and having made that change, the bank thinks risks to the outlook are now balanced.
2 min read

Korea – narrow cycle, but still improving

Korea – narrow cycle, but still improving

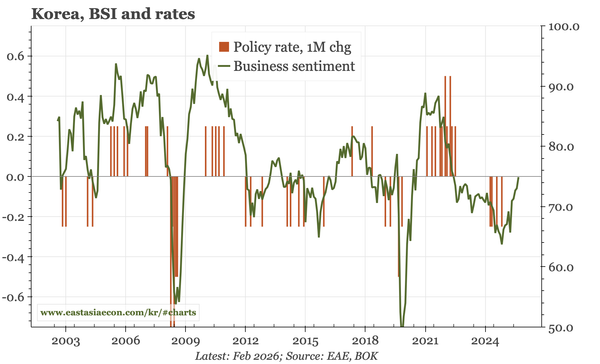
Business sentiment in today's BOK survey returned to the level that has historically divided loosening and tightening cycles. Tomorrow, the bank will likely raise its 2026 growth forecast to above its 2% estimate of potential. The rates market has already priced this, but the currency can move more.

4 min read

Korea – consumer confidence and PPI

Korea – consumer confidence and PPI

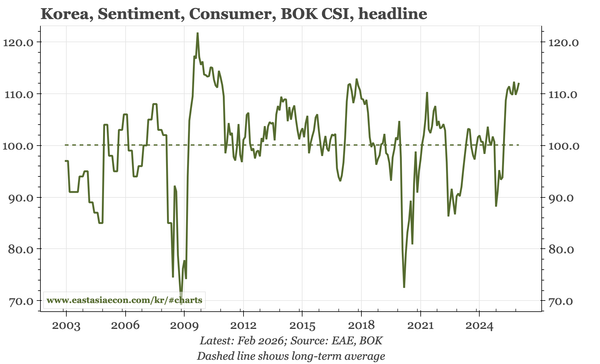
The continued strength of consumer confidence in today's February survey might be hinting at a broader cyclical upturn. At the same time, house price expectations eased. CPI expectations were stable at 2.6%, and likewise, today's PPI for January doesn't point to a big near-term change in inflation.

2 min read

Taiwan – into unchartered waters

Taiwan – into unchartered waters

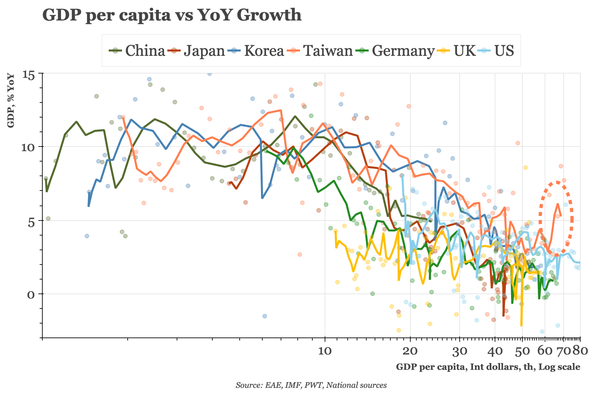
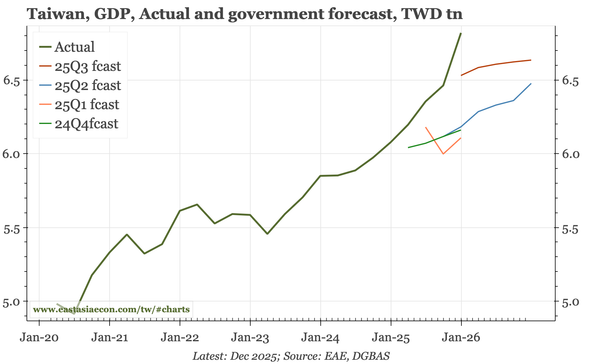
Taiwan's macro story is fascinating. Rarely has growth in such a rich economy accelerated so much, with reindustrialisation and huge external surpluses, at the same time as rates and the currency barely move. I'd think that something has to give. Will 2026 finally be the year that it does?

1 min read

Last week, next week

Last week, next week

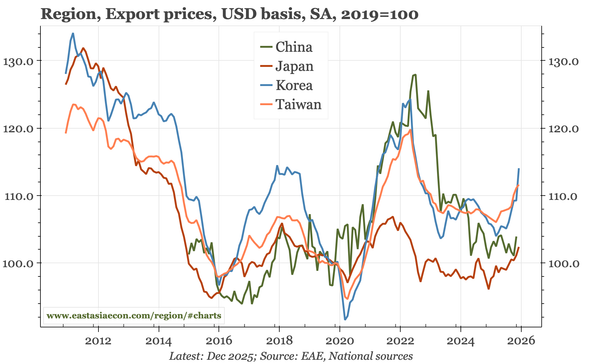
I spent time last week delving into export prices and terms of trade, dynamics that should be offering support for currencies. The data flow was all about Japan, and painted the picture of an economy in good shape. That could yet be undermined by policy choices, either at home, or in the US.

6 min read

Korea – household debt down, property prices up

Korea – household debt down, property prices up

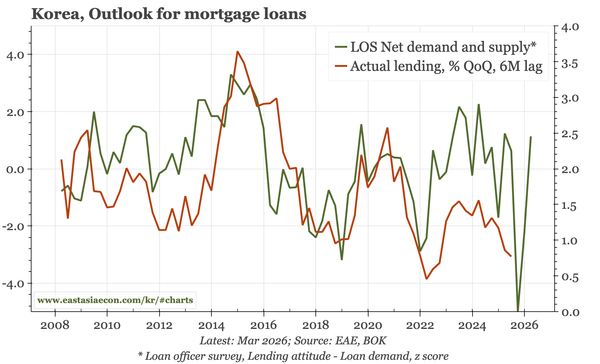
The BOK's quarterly data show household credit eased under 75% of GDP at in 2025 for the first time since 2017. However, the BOK is concerned that the ongoing rise in house prices will undermine this progress. The bank's own loan officer survey suggests a bounceback in lending is indeed a real risk

2 min read

Japan – strong PMIs, weaker inflation

Japan – strong PMIs, weaker inflation

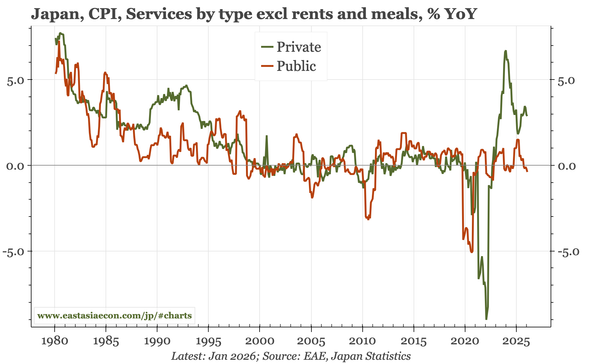
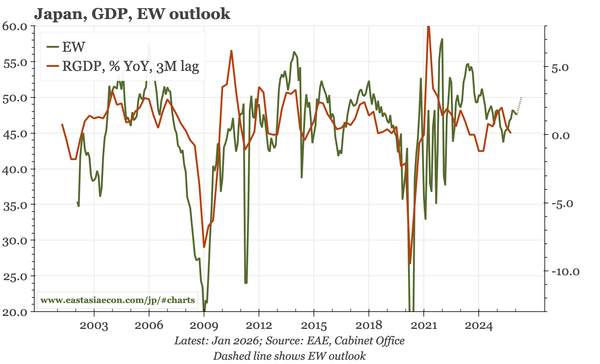
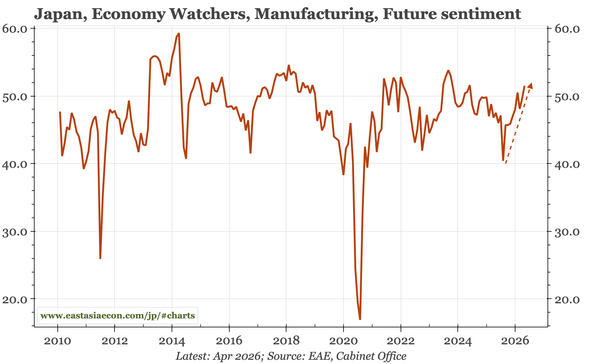
Manufacturing sentiment is up, and falling headline inflation should further boost the mood of households too. For the BOJ, the critical issue will be whether these improvements in soft data feed into real aggregate demand, in turn supporting its confidence about the trend in underlying inflation.

3 min read

Region – Asia and the China Shock 2.0

Region – Asia and the China Shock 2.0

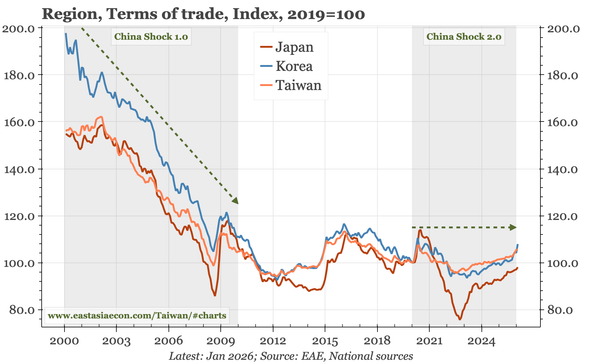
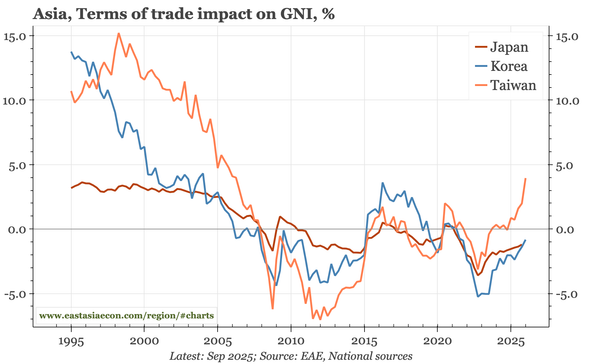
As capital goods exporters, the rest of East Asia is vulnerable to the second China Shock. But the first was deflationary not just because export prices fell, but because import prices also rose, squeezing local incomes. By contrast, the terms of trade this time are stable, and starting to improve.

6 min read

Last week, next week

Last week, next week

Three themes from last week: improving terms of trade, led by rising export prices; expanding current account surpluses; and growing optimism about the sustainability of AI-related hardware demand that is critical for cycles in Taiwan and Korea. Also, happy year of the (fire) horse.

6 min read

China – big inflows, sluggish domestic

China – big inflows, sluggish domestic

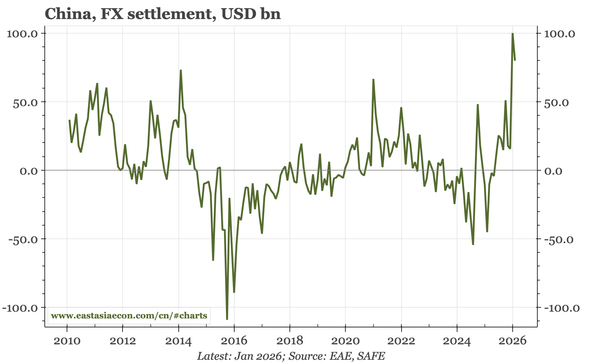
January fx settlement data suggest large fx intervention for a second consecutive month. One reason is the CA surplus, which other data today show widened in Q4. Another is interest rates which are more stable, even though monetary trends aren't changing much, and property prices continue to fall.

3 min read

Japan – import prices up, but export prices up more

Japan – import prices up, but export prices up more

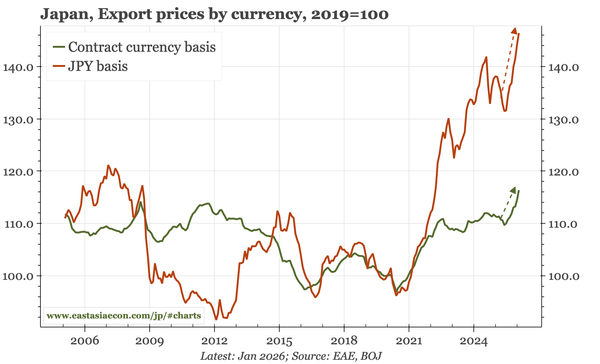
Import prices aren't rising quickly, but they do remain elevated, supporting PPI in a way that wasn't true during Japan's long deflation. More interesting now is the strength of export prices, a dynamic that boosts exporter profits, and via the terms of trade, provides a tailwind for domestic income

2 min read

China – PPI up again

China – PPI up again

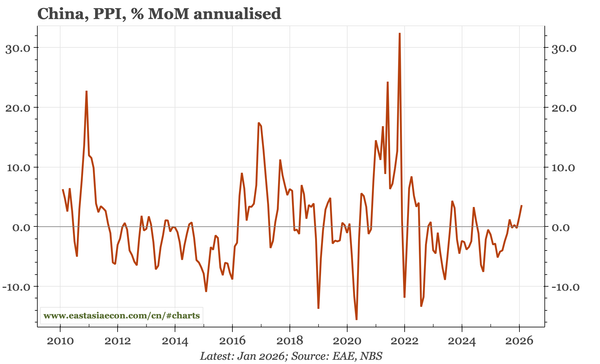
CPI inflation softened in January, but it always does when the new year holiday falls in February. PPI has less seasonal distortion, and rose MoM in January for the second consecutive time. The GDP deflator is likely to improve again in Q1. This is about external factors, but deflation is lessening.

2 min read

Korea – consequences of higher savings

Korea – consequences of higher savings

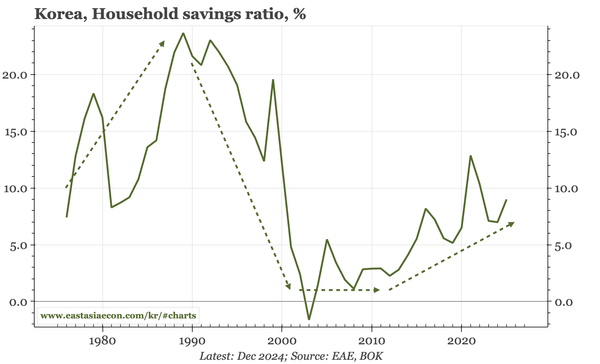
The BOK recently published some nice research highlighting the rise in the household savings ratio. That is an important phenomenon, helping explain the weakness of consumption, the rise in the current account surplus, and being intertwined with the surge in Korea's overseas equity buying.

7 min read

Japan – cycle still strengthening

Japan – cycle still strengthening

Takaichi's huge win comes when the cycle is looking stronger, with real wages close to rising, manufacturing sentiment improving and bank lending strong. This should give the BOJ confidence, and, with the current account surplus in 2025 reaching the highest level in forty years, also help the JPY.

3 min read

Last week, next week

Last week, next week

The fundamental themes for the region are rising external surpluses, improving manufacturing cycles, and lessening deflation in China. That mix should be helping currencies. The offsetting factors to be monitoring are politics in Japan, flows, and global dynamics around tech and the USD.

5 min read

East Asia Econ Data API

East Asia Econ Data API

Formally launching my data API, which now allows access to almost 700,000 series covering China, Japan, Korea and Taiwan, with monthly, quarterly and annual data.

1 min read

Korea – record CA, record equity outflows

Korea – record CA, record equity outflows

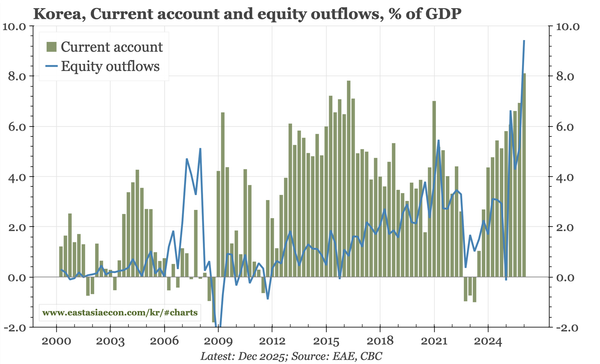
Korea's current account reached a record high in Q4. But equity outflows, remarkably, increased even more. The balance between the two should diverge through 2026. The CA surplus can be expected to grow on the back of the semi supercycle, while there are four reasons to think net outflow should peak

3 min read

Last week, next week

Last week, next week

Regional themes: continuing (and under-appreciated) nominal improvement in China; election uncertainty in Japan; strengthening export momentum in Korea on the back of chips; which in turn looks significant given the huge outperformance of Taiwan through 2025, all because of AI and semiconductors.

6 min read

China – some nominal momentum

China – some nominal momentum

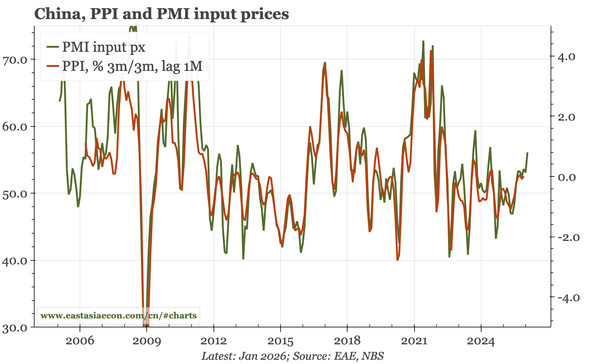
Today's official PMIs were below 50. That shows the domestic economy is weak – though the data were likely pulled down by the coming holiday. More interesting was the further rise in prices in manufacturing. That change relates to USD/global prices, but does suggest an upturn in nominal momentum.

2 min read

Japan – falling inflation = higher consumption?

Japan – falling inflation = higher consumption?

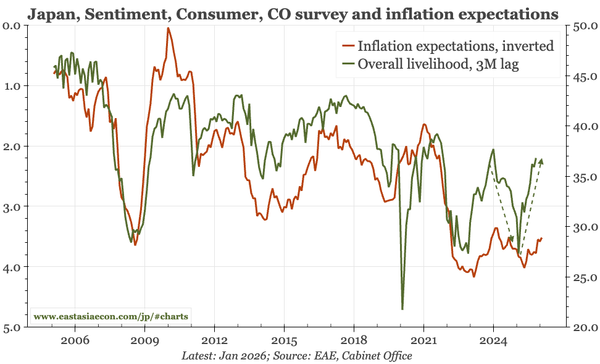
With policy efforts reducing headline inflation, the bullish case for Japan is once again a rise in real wages that pushes up consumer spending and aggregate demand. The consumer confidence survey points to just that scenario, but it isn't in the hard data yet, with December retail sales still soft.

3 min read

Korea – still all about exports

Korea – still all about exports

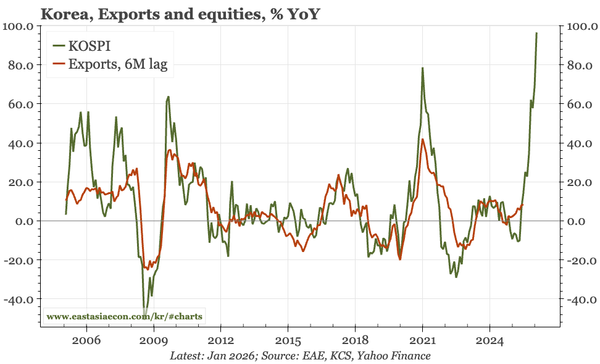
Today's data releases show the domestic economy bottoming out, but not yet growing much. The upside risk rests on 1) exports, which the BOK in its last official forecast thought would only grow 1.4% in 2026 and 2) capex, with Samsung and SK Hynix this week pledging big increases.

3 min read