Archive
East Asia Econ Paul Cavey

Korea – more BOK optimism

Korea – more BOK optimism

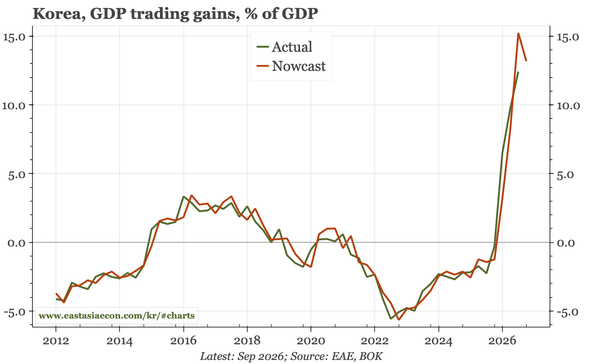
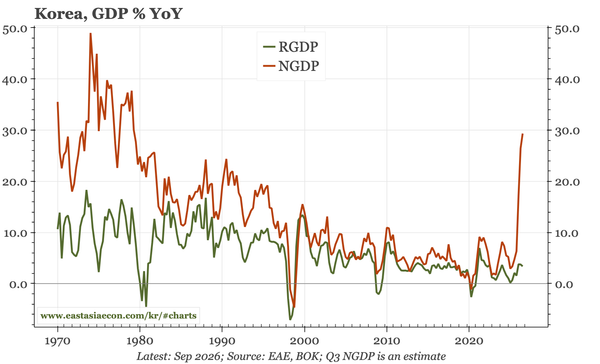
The BOK's latest MPR, including a focus on the "surge in NGDP" shows again the bank's optimism. That tone isn't new, but the confidence matters, especially as it is based on a belief that the cycle isn't as narrow as usually perceived. The caveat is this report was published in Korean in September.
4 min read

East Asia Today

East Asia Today

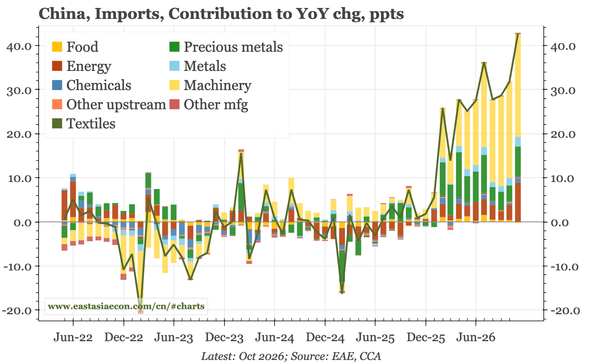
Detailed trade data for China show a slowdown in car exports. Probably, that is a cause. In Japan, by contrast, auto exports have started to show signs of life. Non-mortgage borrowing in Korea did fall in Q3, but the big change in household debt ratios came from the surge in nominal GDP.

2 min read

China – no change in macro

China – no change in macro

The macro story continues to be real weakness in lots of economic data, except industrial production. As long as that is growing near 5%, the government likely thinks the economy is fine. That said, the decline in M1 growth points to slower nominal momentum in 2027, making PBC easing more likely.

3 min read

Last week, next week

Last week, next week

Asia faces not one but two sources of external pressure: the Nvidia fall-out, and expectations for tighter monetary policy. Demand has been strong through November, so there is still room for CBs to hike with the Fed. That, however, isn't true in China, which contrasts with bullish CNY sentiment.

7 min read

Korea – first signs of a peak

Korea – first signs of a peak

The terms of trade dipped in October, hinting at a peak in the spectacular rise in national incomes of recent months. However, when thinking about the implications, two caveats are needed: is the October decline monthly noise, and is the rise in national incomes just the first phase of the semi boom

3 min read

Japan – is corporate saving about to turn?

Japan – is corporate saving about to turn?

In a speech at the weekend Governor Ueda laid open the possibility that Japan might finally be able to achieve its 40-year quest for "domestic demand-led adjustment". That's a big deal. Key is how corporate savings and investment react to higher nominal growth and labour shortages.

13 min read

China – no Japanification

China – no Japanification

With some trepidation, I am releasing my first....rap. Perhaps not the vibe you would expect from me, or from a rap, given both it and the accompanying video are another attempt to argue against the idea of Japanification.

1 min read

Japan – cycle update

Japan – cycle update

I think the curve should flatten, as the BOJ continues to hike because of decent growth and strong inflation, while the longer-end is dampened by medium-term headwinds for inflation and a repatriation flow. These I think remain the themes, though the message from today's releases is mixed.

2 min read

Taiwan – another surge in exports

Taiwan – another surge in exports

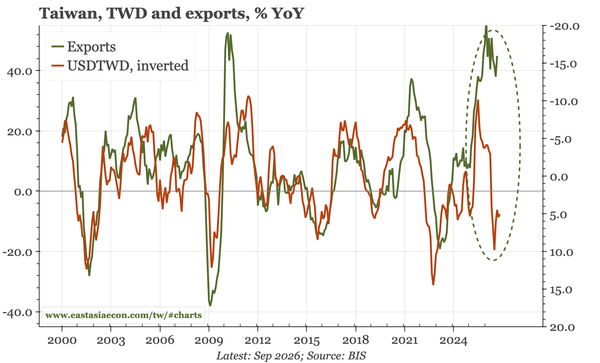
October export growth was the strongest in 20 years. That doesn't tell us what happens next. If 2025 is any guide, even the slowdown suggested by equities might not happen. What the data do say is that AI tech demand remained extremely strong in October, leaving Taiwan with an enormous trade surplus

3 min read

China – inflation all external

China – inflation all external

PPI inflation accelerated again in October, a rise that is supporting nominal GDP and would usually lift corporate profits too. But this is all externally-driven. Downstream prices in PPI and the overall CPI remain weak, and outside of food, leading indicators point to slower inflation in 2027.

3 min read

Last week, next week

Last week, next week

The outlook for macro markets in the region remains closely tied with the fortunes of the AI cycle. While uncertainty remains, rates, currencies and equities will likely trade together. Currencies might end up looking different, depending on how the dollar reacts to any shift in semi demand.

6 min read

Taiwan – how much TWD selling?

Taiwan – how much TWD selling?

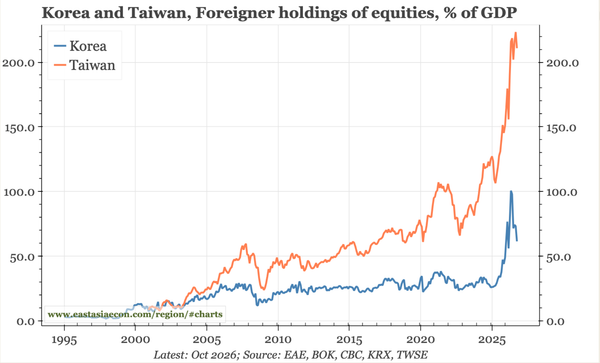
The surge in the Taiex of recent years means potential for big foreigner selling of TWD. But, inflows haven't been big, equities won't all be sold, and CBC has ability to fight back. The bear case is Taiwan recession versus US resilience, though even then, "fundamentals" for TWD would be strong.

6 min read

Taiwan – inflation still over 2%

Taiwan – inflation still over 2%

CPI is being affected by cross-currents including very high upstream price inflation, government subsidies and holidays. The underlying picture is inflation of around 2%, which by Taiwan standards is high. I think an economic slowdown is needed to prevent it moving higher.

2 min read

Korea – CPI still cost-push

Korea – CPI still cost-push

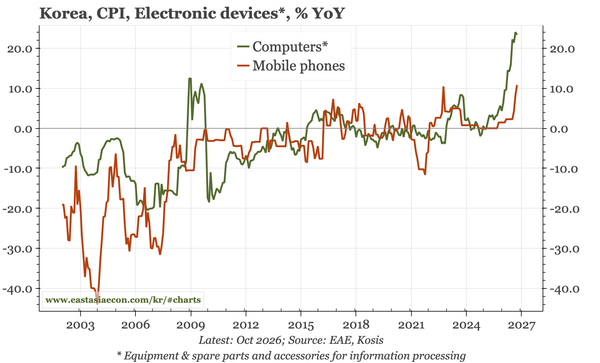
Cost-push – both energy and the spillover from higher chip costs into prices of downstream devices – is keeping inflation near 3%. The BOK expects demand-pull factors to become more obvious. So inflation will likely stay elevated, through for BOK policy, it is overall semi cycle that matters more.

2 min read

Taiwan – consumer v AI demand?

Taiwan – consumer v AI demand?

Taiwan's overall PMIs look fine. The details are shakier, but so far, it looks like the weakness is coming from softer demand for consumer tech as semi prices boost the cost of electronics devices. The data don't (yet) show obvious deterioration in the data centre component of the AI boom.

4 min read

Japan – no obstacle to more hikes

Japan – no obstacle to more hikes

The unusually long section of analytical boxes in the BOJ's main outlook report shows that the bank has a lot on its mind. That inevitably brings nuance. However, the overall tone is clear: nominal growth remains strong, and financial conditions loose. There's no clear reason not to hike further

6 min read

Last week, next week

Last week, next week

China's nominal cycle looks to be slowing again. The rest of the region remains strong, but confidence that this strength can be retained is fraying, and will likely remain under pressure, especially if concerns over the data centre build-out and energy prices worsen again after the mid-terms.

6 min read

China – px firm, construction not

China – px firm, construction not

Headline official PMIs continue to closely hug the 50 threshold. I am not sure that tells us much about the economy. But two components of the PMI are useful. The ongoing slump in construction indicates no property revival. Price indicators show PPI still strong, but warn of some weakening in CPI.

2 min read

Taiwan – growth re-accelerates

Taiwan – growth re-accelerates

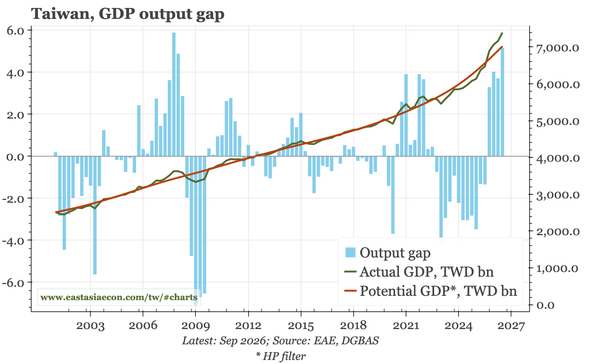
Rather than slowing as the government had forecast just a couple of months ago, GDP growth re-accelerated in Q3 to 14.4% YoY. That was because of domestic demand rather than net exports, and while that was mostly capex, consumption is growing more than 5%, and the positive output gap widened.

2 min read

Japan – 2%...but no more?

Japan – 2%...but no more?

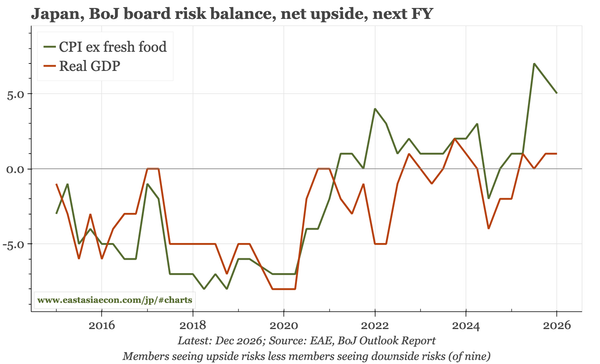
The BOJ argues today not just that "underlying inflation" has reached 2%, but that it is expected to stay there. However, it seems clear that stability won't be achieved without some help, as its analysis also says that all the risks to prices are to the upside.

3 min read

Korea – strong, but still unbalanced

Korea – strong, but still unbalanced

Earnings releases and September macro data show the cycle has strong momentum. Growth is dominated by semis, and so dependent on the global cycle. However, the doubling in tax revenue in September shows one way in which the benefits of the semi cycle can start to broaden out.

4 min read

Japan – medium-term concerns

Japan – medium-term concerns

With both growth and inflation strengthening, it will be tough for the BOJ not to hike faster – whatever Takaichi thinks. However, back-to-back or 50bp moves are unlikely. Moreover, the peaking of property prices and sluggishness in some wage indicators point to MT headwinds.

8 min read

Taiwan – strong, but no trigger

Taiwan – strong, but no trigger

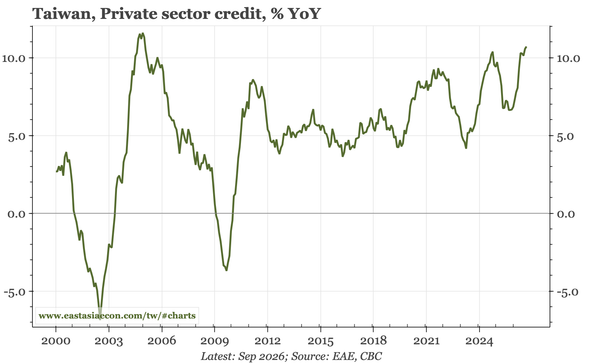
September money and credit data for September are like other indicators for Taiwan: quite strong, but not high enough on their own to think that they suddenly break the CBC's apparently strong desire not to change policy.

2 min read

Korea – still the income tailwind

Korea – still the income tailwind

Today's Q3 GDP data continue the same story: real growth is solid, but more importantly, the huge windfall income gain from the surge in semiconductor prices remains a major tailwind for growth in 2027. The question remains how much of that income windfall will be spent.

4 min read