Paul Cavey

Paul Cavey

Japan – more talk of upside risks for inflation

Japan – more talk of upside risks for inflation

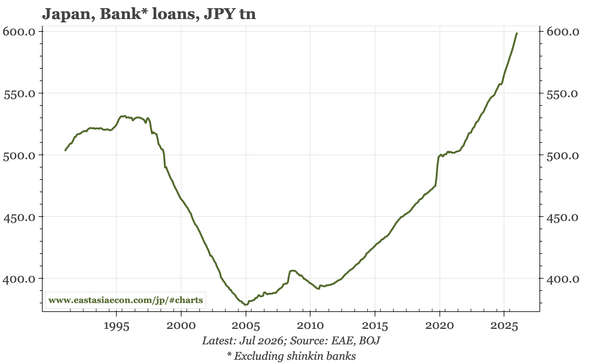
Today's summary of opinions of the July meeting had two themes: first, AI-related demand, and second upside risks to inflation – and the need for monetary policy to control them. The data flow showed a modest slowdown in bank lending, a somewhat sluggish EW survey, and a fall in the CA surplus.
3 min read

Last week, next week

Last week, next week

China macro is again a contrast between export strength and renewed deflationary pressure. Takaichi's sales tax cut doesn't look like the policy approach Bessent wants. For Korea, data an BOK analysis points to upside risks. In Taiwan, the key issue is lagged spillover from the 24-25 export boom.

7 min read

China – inflation much weaker in July

China – inflation much weaker in July

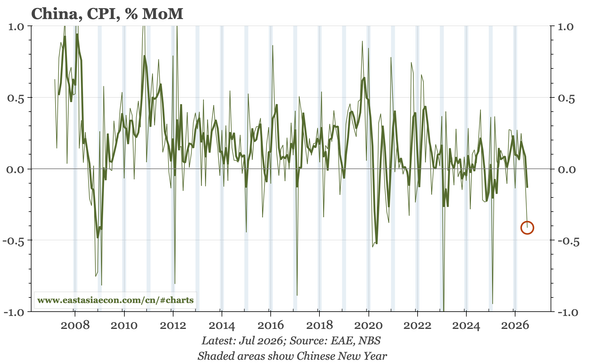
Inflationary pressure turned down again in July. That wasn't a surprise, given the decline in global energy prices. The sharp MoM drop in CPI was, however, still notable, being comparable only to the global financial crisis and the initial covid outbreak.

3 min read

East Asia Today

East Asia Today

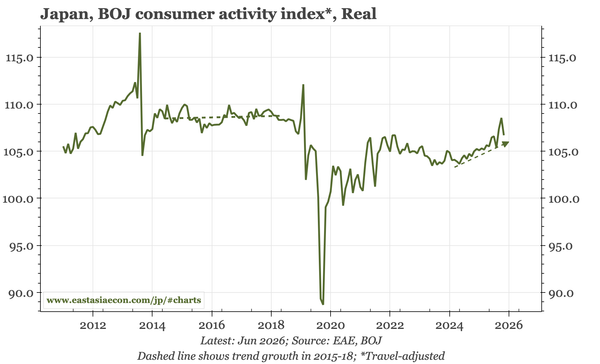
The longer note today looks at a BOK report on spillovers from the chip boom. Exports in both China and Taiwan were softer in July, but probably because of noise. Japan released consumption data for June, exports for the first 20 days of July, and BOJ transaction data for the full month.

3 min read

Korea – the BOK's view of the TOT boom

Korea – the BOK's view of the TOT boom

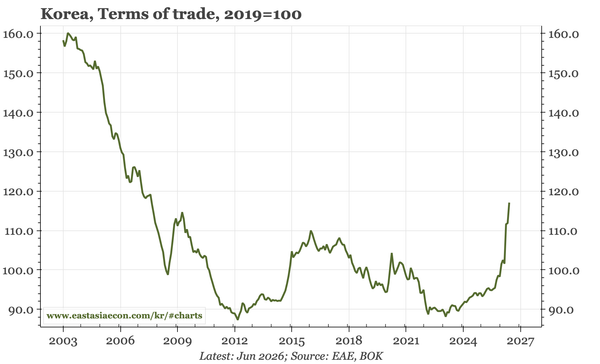
The BOK this week published a nice report on spillovers from the terms of trade boom. It wouldn't be fair to say that this pays only lip service to the usual concerns on why spillovers might be limited. But the report's central expectation is that the impact will be "both sizable and persistent"

5 min read

East Asia Today

East Asia Today

Korea's current account surplus, already enormous in May, rose further in June. That, and the easing of foreigner equity selling, has allowed (at last) some strengthening of the KRW. Taiwan headline inflation ticked down in July, but underlying price pressures remain firm.

2 min read

Taiwan – firm inflation pressure

Taiwan – firm inflation pressure

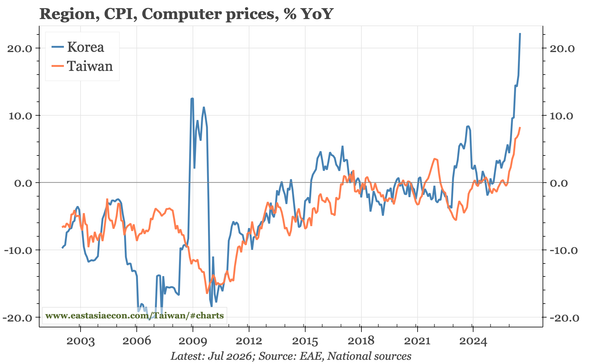
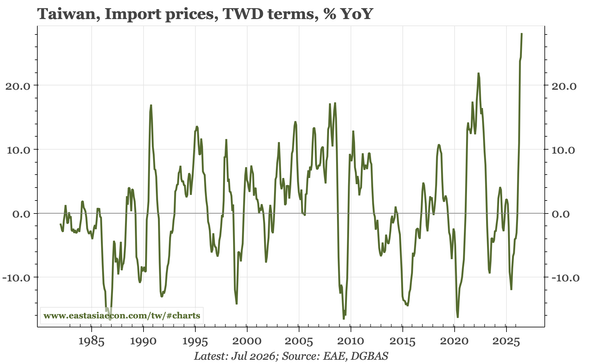
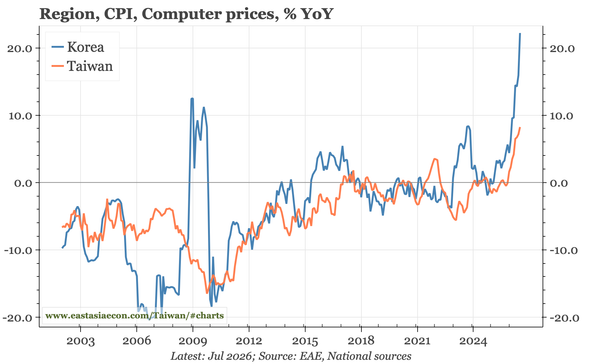
Both headline and core CPI inflation ticked down in July as energy prices eased. However, underlying inflation feels firm, with sequential core failing to break below 2%; import price, PPI inflation and CPI computer price inflation rising to decade highs; and services inflation running at 2.6%.

2 min read

East Asia Today

East Asia Today

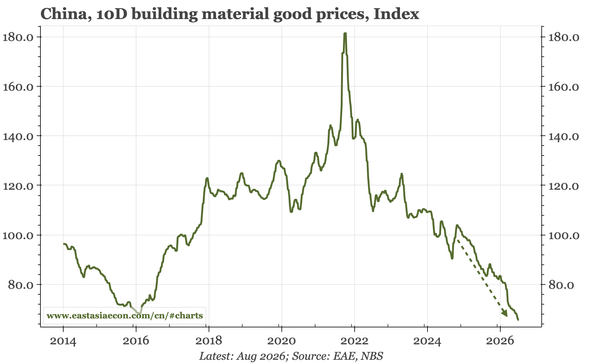
What global commodity prices tell us about the outlook for upstream inflation in the region; data in China showing another fall in building materials prices, and a sharp decline in the services PMI; decent wage growth data for Japan; and in Taiwan, another fall in fx reserves in July.

3 min read

Japan – firm wages, stronger prices

Japan – firm wages, stronger prices

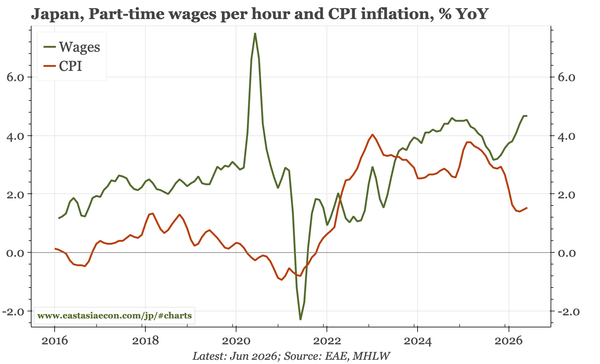
Underlying regular wage growth at a bit under 3% is probably still a touch lower than the BOJ would like. But part-time hourly wage growth is 5%, and anyway, with today's services PMI showing more sharp rises in output prices, underlying wage growth isn't the only factor that matters for inflation.

3 min read

East Asia Today

East Asia Today

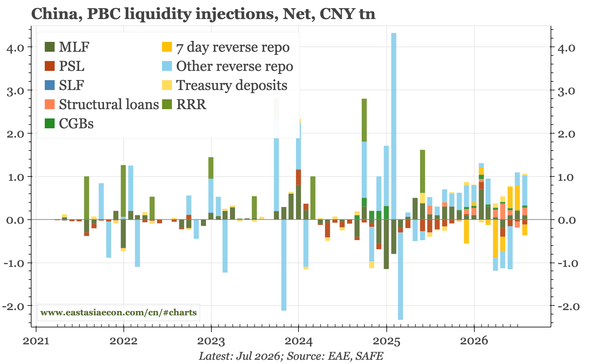
The main data release today was Korea July CPI, with one takeaway from that being the clear evidence of cost-push pressures from the chip boom. Elsewhere, the PBC again injected liquidity in July, Japan's monetary base contracted at a double-digit rate, and an update on Taiwan's property market.

3 min read

Korea – cost-push more than demand-pull

Korea – cost-push more than demand-pull

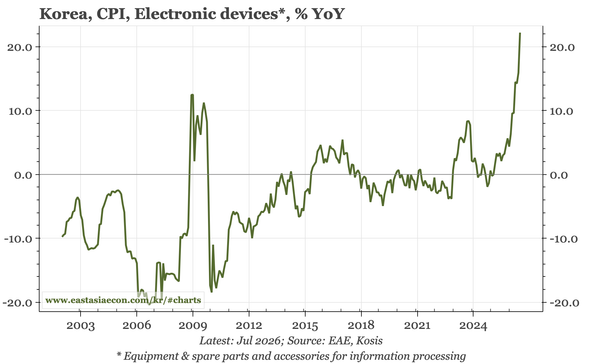
The BOK expects core inflation to be pushed up by the chip boom, via both cost-push for electronic devices and demand-pull from the big boost to national incomes. In today's July data, the cost-push element is more obvious, though there are some tentative signs of demand-pull appearing.

2 min read

East Asia Today

East Asia Today

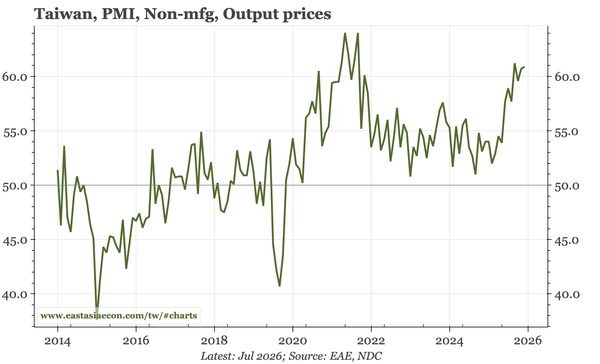
China's RatingDog mfg PMI dipped in July, and isn't far above 50, though that's still higher than the official version. PMIs elsewhere remain better. The main driver is exports, which in Korea rose again in July. But Taiwan's non-mfg PMI is also strong, at a headline level, and for output prices.

3 min read

Japan – more inflation risks from the BOJ

Japan – more inflation risks from the BOJ

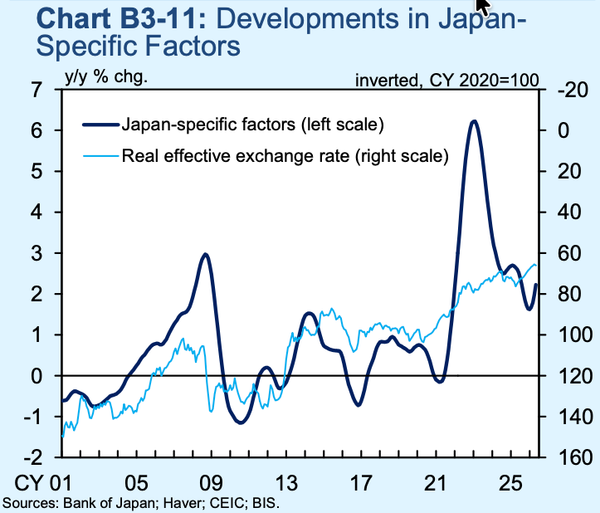
The analytical boxes from the BOJ's full outlook report have three conclusions: AI won't help macro as much as headline figures suggest; but both AI and oil mean continued upside risks for inflation; and the household sector should be able to cope with rate hikes.

5 min read