Paul Cavey

Paul Cavey

East Asia Today

East Asia Today

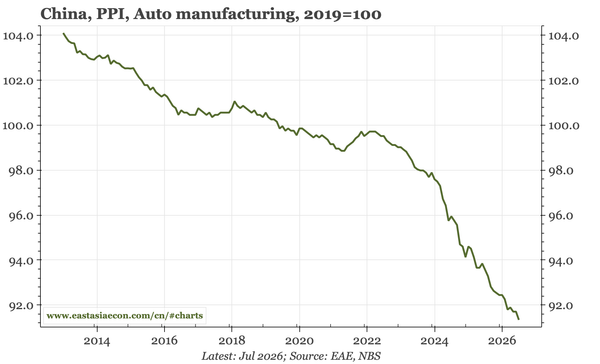
Relative GDP performance across the region, and a few more updates on China: detailed auto export data and fx settlement data for July, and upstream prices through the first 10 days of August.

2 min read

East Asia Today

East Asia Today

Another round of weak domestic demand data for China. Japan Q2 GDP growth softened, but I thought the details looked ok. Taiwan's FDI into the US is once again increasing sharply.

2 min read

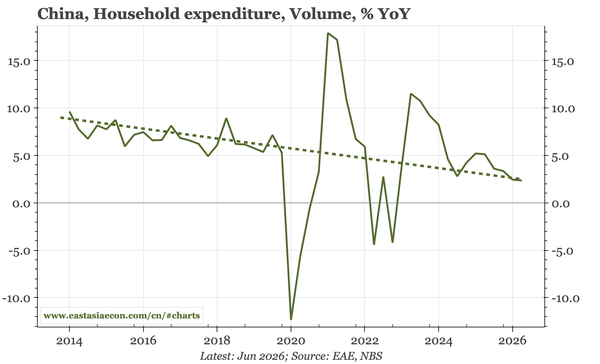
China – domestic demand still weakening

China – domestic demand still weakening

Retail sales have been anchored around zero for more than a year, property activity is still dropping and FAI is contracting. Nonetheless, IP is growing around 5%, partly because of exports, and the government's attitude suggests that it continues to think that is enough.

3 min read

Last week, next week

Last week, next week

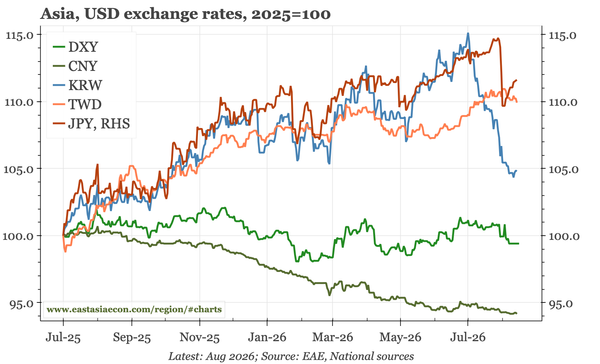
China macro isn't weak enough to trigger a change in policy direction. The JPY is weak enough to speed up BOJ tightening and puts pressure on Takaichi to change fiscal rhetoric. KRW is starting to look more interesting than rates, while in Taiwan, domestic demand puts the focus on rates.

7 min read

East Asia Today

East Asia Today

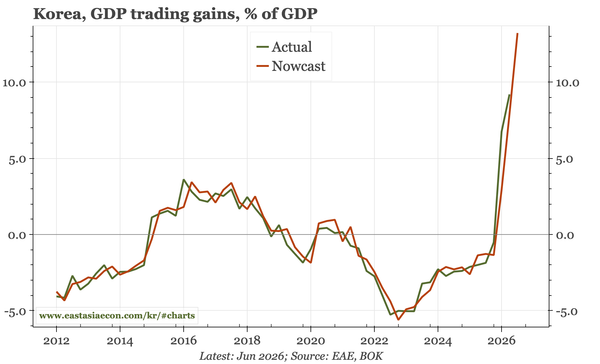
China's July money data were soft, but not much worse. Terms of trade data for Korea show strong GNI/nominal GDP growth continues. Headline growth in Taiwan is slowing from crazy rates, but domestic demand is stronger. Also, my guide to China's consumer data.

3 min read

Taiwan – not over yet

Taiwan – not over yet

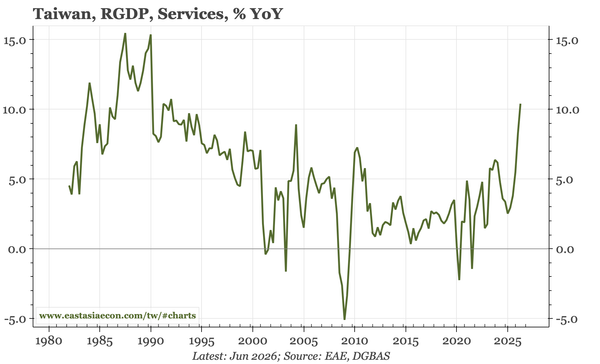
Headline growth rates are slowing, but the government's qualitative assessment remains bullish, there are more signs of life in domestic demand and services, and while a 2026 inflation forecast of a bit over 2% isn't so high, it has been raised four quarters in a row, and is above the policy rate.

3 min read

Korea – TOT-led growth continues

Korea – TOT-led growth continues

The big macro dynamic is the sharp rise in chip prices that is boosting the terms of trade, and thereby lifting nominal GDP and national income. Today's July export and import price data show that these trends remain in place. Rates have priced at least the first stage of this. The KRW still hasn't.

2 min read

China – consumption guide

China – consumption guide

China's economic data are widely cited – but aren't well understood. To try to tackle that, I have been making some data guides. This first one tackles consumption.

161 min read

East Asia Today

East Asia Today

The main data release today was PPI, import and export prices in Japan, which show inflationary pressures easing from June, but remaining high. As would be expected given the big rise in nominal GDP, tax revenue in Korea is growing strongly.

2 min read

East Asia Today

East Asia Today

The Japan Reuters Tankan shows the recovery in manufacturing sentiment that was interrupted by the Iran War is back on track. In Korea, unemployment remains below 3%, and that will be a truer measure of labour market tightness if some of the structural supply side shifts continue to lose momentum.

2 min read

East Asia Today

East Asia Today

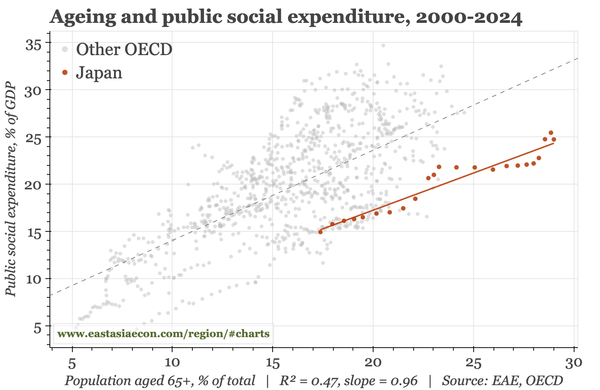
Today, some charts on a longer examining fiscal policy in Japan. In today's data releases, exports in the first ten days of August ticked down. Likewise, growth in tax revenue in Taiwan slowed.

2 min read

Japan – fiscal reality v rhetoric

Japan – fiscal reality v rhetoric

A longer note on fiscal policy: the rhetoric of loosening versus reality of tightening of Abenomics and the early part of Takaichi's administration, the costs of that for the household sector versus the benefits for corporates, and what all that means for Takaichi's stance going forward.

11 min read

East Asia Today

East Asia Today

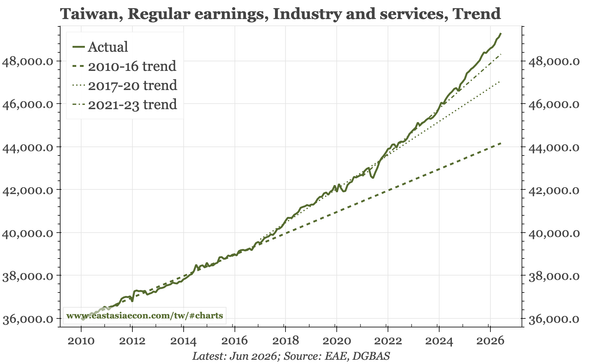
Summaries of three notes, covering: 1) yesterday's weak July inflation print in China; 2) today's summary of opinions of the July BOJ meeting and a few data releases in Japan; and 3) Taiwan's June wage data showing the slow but steady acceleration in wage growth is continuing.

2 min read

Taiwan – wage growth above 3%

Taiwan – wage growth above 3%

Annualised regular wage growth in both manufacturing and services has been above 3% since 2024. In Q2 in manufacturing, it has been near 4%. The risk remains that the export cycle now slows, but TSMC's strong sales and elevated manufacturing overtime don't suggest that is happening yet.

3 min read