Paul Cavey

Paul Cavey

East Asia Today

East Asia Today

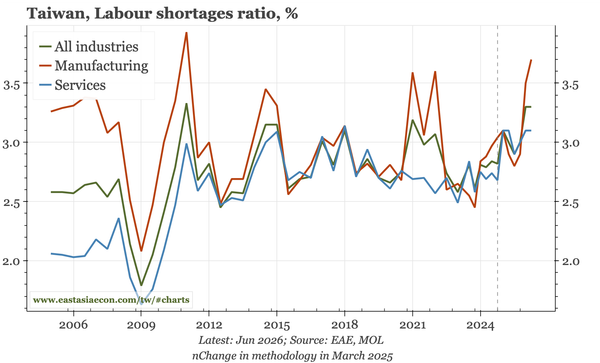
China's credit data remain weak, and deposit trends point to deflation risk in 2027. BOJ Koeda's speech was hawkish. Korea money supply growth slowed, and with equities falling, FCI has tightened. That market nervousness on AI isn't shared by TSMC management, and the labour market remains tight.

3 min read

East Asia Today

East Asia Today

Exports across the region have been extraordinarily strong through September. Along with trade, inflation data for China show external factors remain the strongest dynamic in China's overall cycle. YoY money supply growth in Japan slowed last month.

2 min read

China – external boost

China – external boost

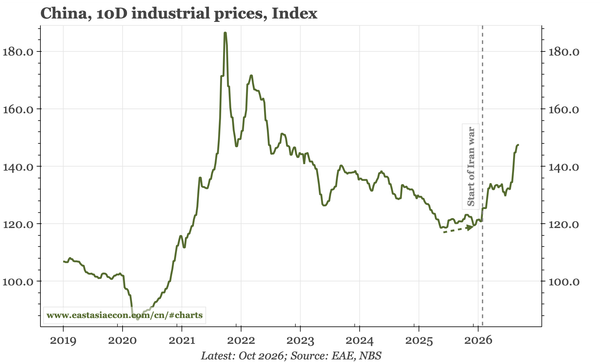
That external factors continue to be the driving force of China's cycle dynamics was once again evident in the strength of both exports and PPI inflation in September. The combination puts a floor under overall nominal growth, and makes it unlikely that domestic policy becomes more aggressive.

3 min read

East Asia Today

East Asia Today

Regional import price inflation has eased, but will likely rebound before year-end. Export price inflation is accelerating, being lifted by chips and other AI-tech. Consumer price expectations and bank lending in Japan remain strong. Taiwan tax revenue is growing by 20% YoY.

3 min read

East Asia Today

East Asia Today

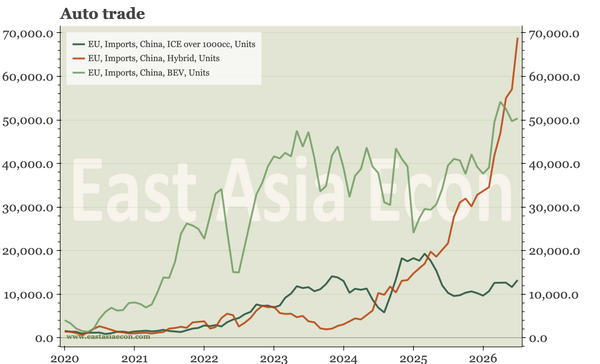
Issue covered today: EU-China auto trade, machine tool orders in Japan, trade for the first ten days of October for Korea, and September reserve money data in Taiwan. Also (again) a link to the podcast I did last week with Macro Hive.

4 min read

East Asia in Four Charts

East Asia in Four Charts

China's auto trade balance with Asia and the EU, the manufacturing upturn in Japan, another large current account surplus in Korea, and further acceleration in Taiwan's exports. Also, I was very happy to have the chance to go back on the Macro Hive podcast, with the link included here.

2 min read

Last week, next week

Last week, next week

I don't think the China-EU sectoral deal means a China-EU CNY deal is coming. The cycle continues to improve in Japan. Export momentum in Korea and Taiwan remain strong, with more signs of spillover into inflation in Taiwan. Links to all last week's research, as well as my latest podcast appearance.

6 min read

East Asia Today

East Asia Today

China's upstream price data confirm the rebound in costs seen in the PMI. Nonetheless, the PBC continued to inject liquidity in September. Details of aggregate household incomes in Japan in Q2 are useful for understanding Japan macro, though the data don't all point in one direction.

2 min read

Japan – household incomes still weak

Japan – household incomes still weak

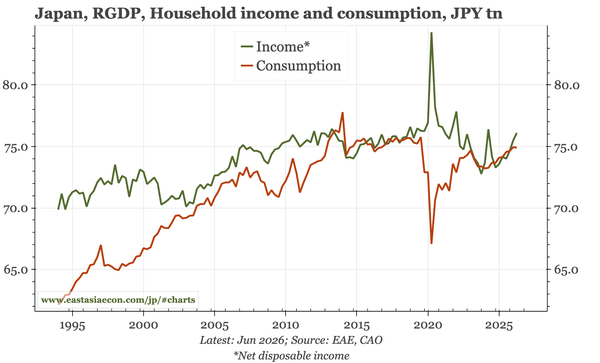
Q2 aggregate consumption was weak because incomes were too. Asset incomes are rising, but wages are soft, and in cash terms, the tax burden has been increasing. But while spending in aggregate terms is constrained, the population is falling, so in per capita terms there is actually recovery.

3 min read

East Asia Today

East Asia Today

The BOJ's regional report, an important input into the monetary policy process, showed strength in industrial activity and inflation. Korea's August CA surplus rose again, implying higher nominal GDP growth. Far from slowing down, Taiwan's exports in September accelerated again.

3 min read

Korea – net exports v flows

Korea – net exports v flows

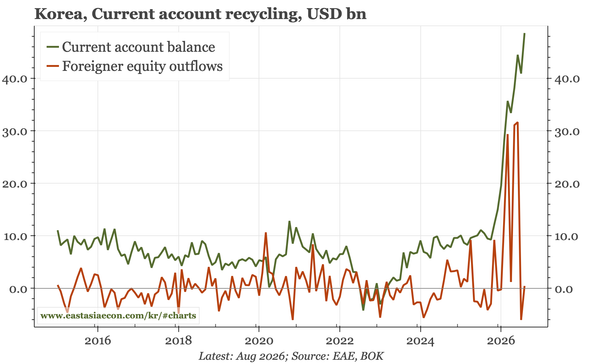
The strength of the current account in August shows Q3 will be another blowout for nominal GDP, improving all Korea's macro ratios. That provides cyclical and structural reasons for KRW strength and relative outperformance of longer-term KTBs. The headwind remains equity outflows.

3 min read

East Asia Today

East Asia Today

There were a few releases in Japan today that were worth summarising. Taiwan's September CPI data was important, showing inflation remaining firm. Korea's Q2 flow of funds offered another illustration of the broad impact that the chip boom is having on the macroeconomy.

2 min read

Taiwan – inflation higher again

Taiwan – inflation higher again

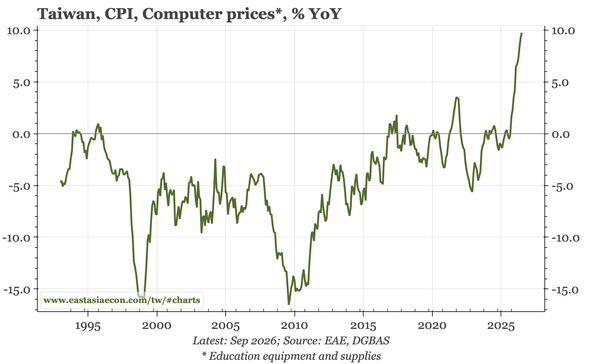
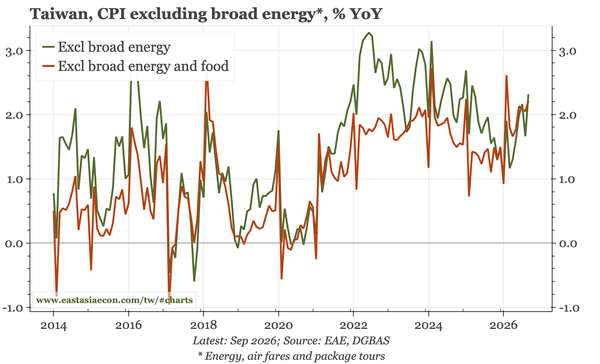
Taiwan's price data still don't suggest the economy is overheating. But pipeline pressure is strong, computer prices are surging, indirect energy prices can't be easily controlled by policy, and underlying inflation still looks firm. That all stands out when real interest rates are still negative.

2 min read