Paul Cavey

Paul Cavey

East Asia Today

East Asia Today

As expected CPI inflation in Japan picked up in September, and leading indicators point to further upside ahead. Taiwan softened last month, but that is at odds with strong exports. Retail sales, by contrast, were strong, consistent with labour market dynamics explored in a longer note on wages.

3 min read

Taiwan – wage dynamics

Taiwan – wage dynamics

Like so much else in Taiwan, labour market dynamics will be determined by the fortunes of the AI cycle. If that turns down, it will be hugely important. A sharp downturn hasn't, however, been the CBC's expectation, but existing wage trends seem inconsistent with the bank's view that inflation slows.

4 min read

East Asia Today

East Asia Today

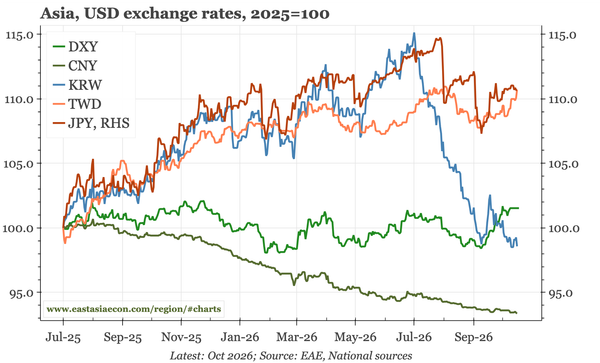
The BOK didn't change rates today, but laid out a much more positive view on the outlook than is being expressed by regional equities. One casualty of the equity sell-off is the TWD, which will further push up inflationary pressure in Taiwan. Also today, the BOJ's senior loan officer survey.

2 min read

Korea – BOK confident

Korea – BOK confident

There was no change from the BOK today, and the decision to stay on hold was unanimous. That wasn't a surprise. However, the meeting was informative, with the clear takeaway being BOK confidence that this cycle will run through 2027.

3 min read

East Asia Today

East Asia Today

A note reviewing developments in Korea ahead – just about – of the BOK meeting tomorrow. In addition, some charts showing the continuing gap between weak auto sales in China v strong car exports. That is affecting Japan, though overall exports there in USD terms rose again in September.

2 min read

Korea – the boom that hasn't happened

Korea – the boom that hasn't happened

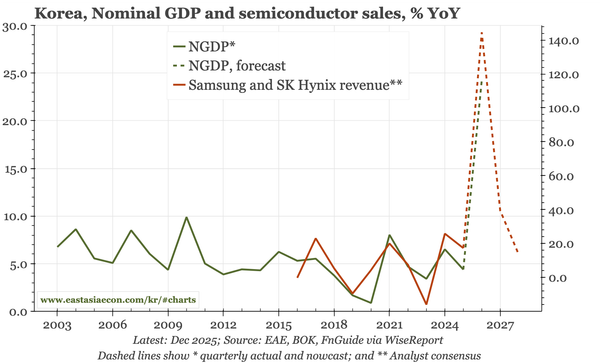
The BOK is unlikely to move tomorrow when it hiked twice recently, the KRW has finally firmed, and there is nervousness about the AI cycle. However, if those worries are just a wobble, then there's still much room for the semi surge to feed into domestic demand, and tomorrow will just be a pause.

6 min read

East Asia Today

East Asia Today

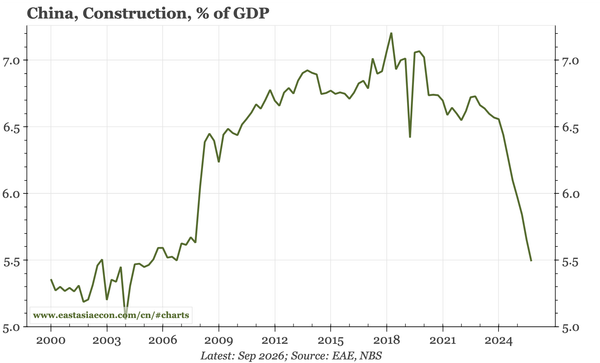
The usual second-day release of more detailed GDP data for China showed investment particularly weak in Q3. In contrast, fx settlement data in September was firm, showing continued capital inflows. In Taiwan, export orders last month don't indicate that the cycle is yet turning down.

2 min read

East Asia Today

East Asia Today

The highlight today was the Q3 GDP release in China. Along with an update of all the usual cycle charts, I've also updated my guide to China's consumption data. In Japan, growth in services activity eased back in August, with a rare contraction in consumer-related services activity like eating out.

3 min read

China – enough for 2026, but not 2027

China – enough for 2026, but not 2027

From the perspective of a government that wants to meet a 2026 growth target without having to shift policy, the September data are encouraging. But the 2027 outlook for the domestic economy is looking more challenging. That will become more visible if global demand and price trends change.

3 min read

East Asia in Four Charts

East Asia in Four Charts

Highlights of last week's indicators: China's import shortfall, loose financial conditions in Japan, rising export prices in Korea, and more evidence of labour market tightness in Taiwan.

2 min read

Last week, next week

Last week, next week

With regional macro dependent on continuation of the US AI build-out, the equity sell-off last week matters. That said, there are still complications: TSMC still sounds very bullish, and while for bad economies, it isn't clear that an end of the AI cycle would be so negative for currencies.

6 min read

East Asia Today

East Asia Today

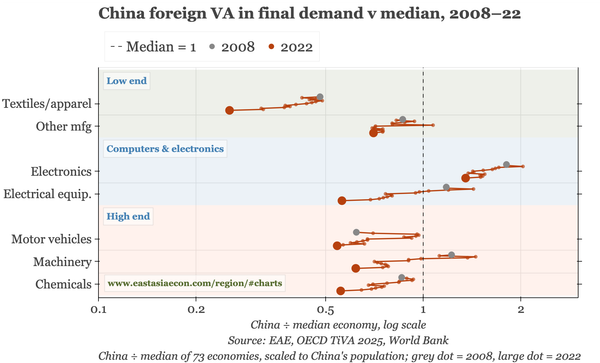
Some highlights of the chart pack I've been working on looking at the China Shock (and China Squeeze). The China Shock isn't over, with data today showing R&D spending reaching a new high of 2.8% of GDP in 2025. In Korea, the TOT rose further in September, and unemployment remained low.

2 min read

China – squeeze, shock or shortfall

China – squeeze, shock or shortfall

A chart pack focused on China's trade: the China Squeeze isn't so severe; the China Shock is, but is likely to intensify further; as important as both is a shortfall in imports, which is broad-based, and worsening. That reflects weak demand, which Beijing still shows no urgency in addressing.

1 min read