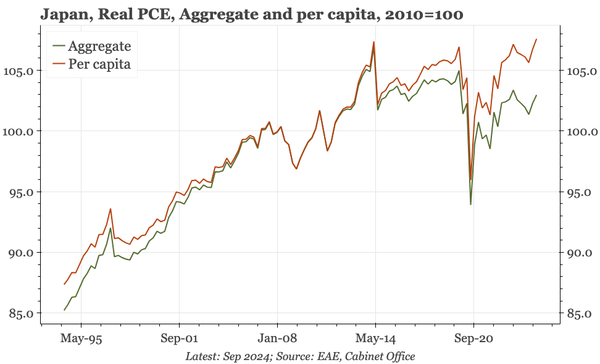
Japan – consumption at all-time high
GDP grew again in Q3. Much of the rise since Q2 is because of a recovery in consumption, but that continues to be much more visible in per capita terms: aggregate consumption is still below the pre-2020 highs, dragged down by a fall in the population, a decline that the BOJ obviously can't address.
Japan – BOJ still constructive, despite modestly softer data
The opinions from the October BOJ meeting show a bit less concern about US uncertainty. That seems premature, given the election, but comments on the domestic economy also don't suggest any change in the bank's fundamental view. Survey data have been a bit softer, but not yet uniformly.
Japan – BOJ gets back to labour and wages
The boxes in the BOJ's full outlook report that look at the labour market and wages don't suggest any weakening of the bank's underlying confidence – increasingly evident before July – that Japan's inflation is sustainable. The implication is that rate hikes remain on the agenda.
Japan – no surprises from the BOJ
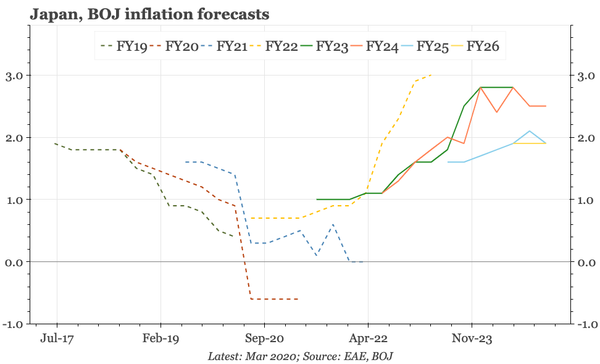
No surprises from the BOJ (yet): the July forecast for underlying inflation to remain around 2% was maintained, as was the policy caution since August that stresses uncertainty in outlook for the US. There's still the press conference and full outlook report to come.
Japan – core inflation still at 2%
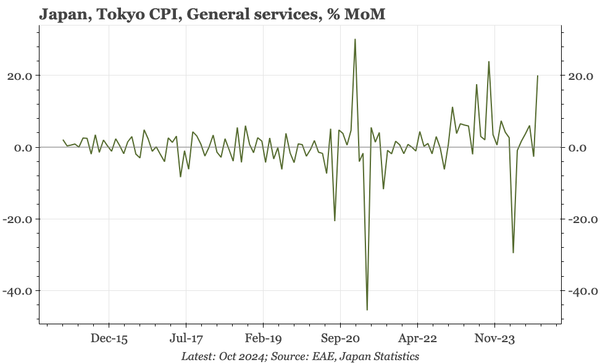
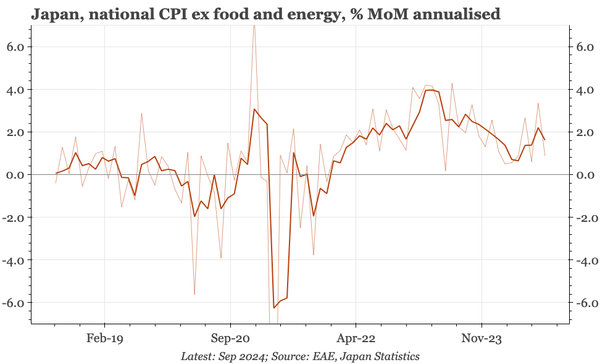
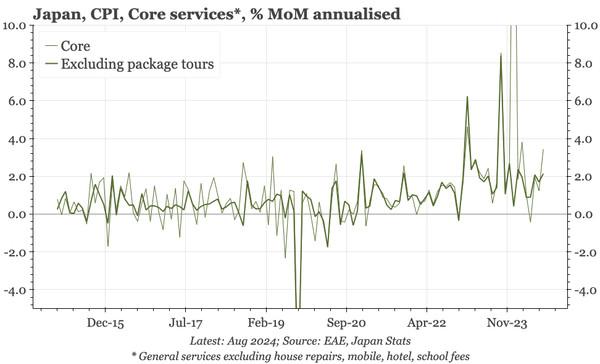
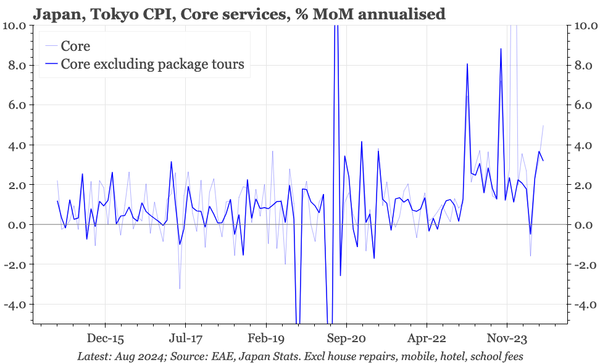
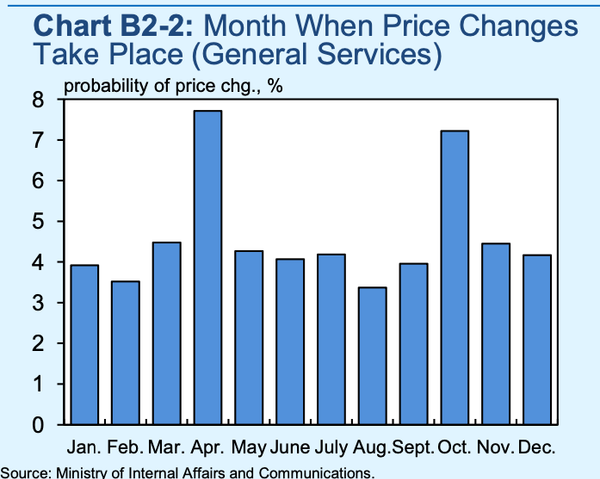
With the BOJ emphasising the twice-yearly patten of service prices hikes, with the second round falling in October, today's Tokyo CPI data are important. They do show services prices rising, and although the details are messy, core sequential inflation in Tokyo is also continuing to run near 2%.
Japan – what can the BOJ say now?
Inflation was softer in September, but the economy still looks on track, with exports and household income up, and early signs of another strong shunto round. At the same time, the JPY is weakening again. This backdrop means the BOJ faces a very tough communication challenge at its October meeting.
Japan – incomes up, but still not enough
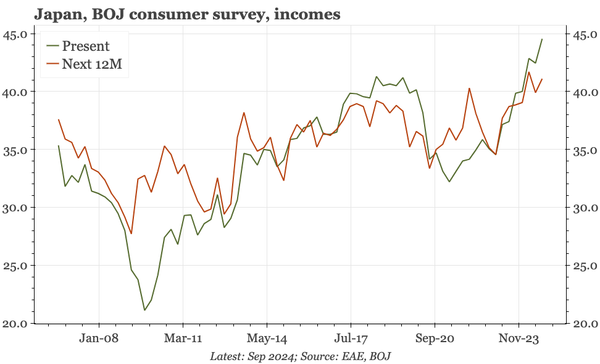
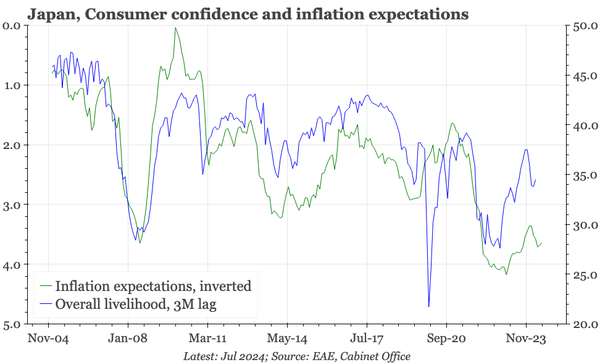
There was a decent bounce in per capita household incomes through Q2. But the rise in consumption was smaller, with better incomes fuelling stronger savings rather than much more spending. The Q2 BOJ consumer survey shows the big worry at the household level remains the high level of prices.
Japan – EW and wages remain firm
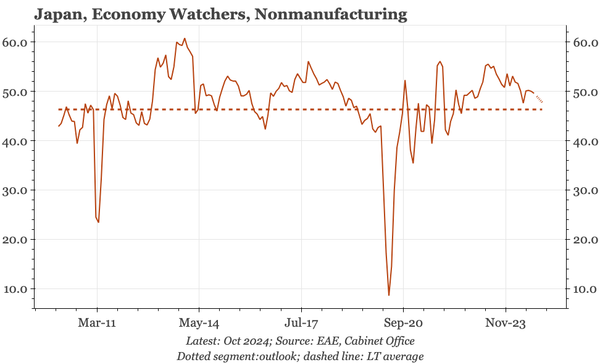
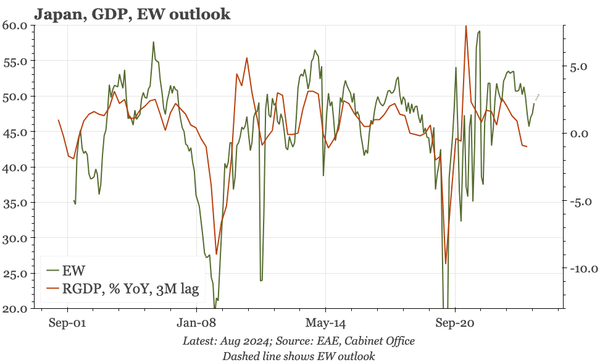
Data continue to show little change in the constructive economic assessment that the BOJ was talking about in 1H24. The Economy Watchers survey for September ticked down, but is well above the LT average, and the outlook score is higher still. Growth in underlying wages remains firm.
Japan – Q3 Tankan details
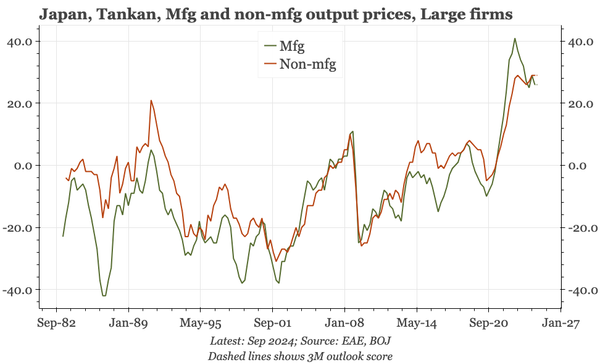
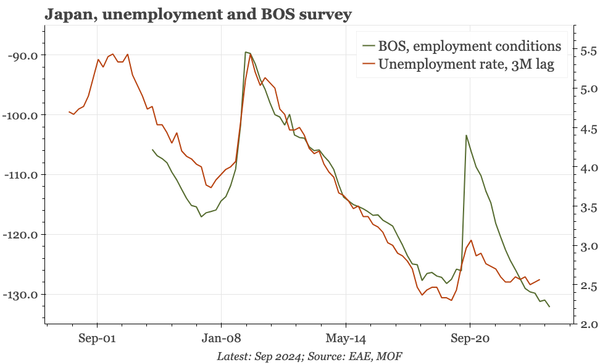
The detailed Q3 BOJ Tankan shows both labour market tightness and corporate output price expectations remaining as elevated as any time since the 1980s. Clearly, the economy hasn't been derailed by the market volatility of early August, and without a new shock, the BOJ seems likely to hike again.
Japan – Q3 Tankan on track
Ueda's caution and now politics are the big near-term policy dynamics. Politics might affect monetary policy longer-term, if Ishiba's as PM is as hawkish as his reputation. But the cycle hasn't been derailed yet, with the Q3 Tankan showing sentiment, the labour market and pricing all remaining firm.
Japan – cold feet
The BOJ's stance now has two clear dimensions. One, as before, is its constructive view of the domestic economy. But now there's also an explicit concern about US growth. As long as one offsets the other, the BOJ has time. However, if the US soft lands, then the BOJ will have ground to make up.
Japan – services inflation back to 2%
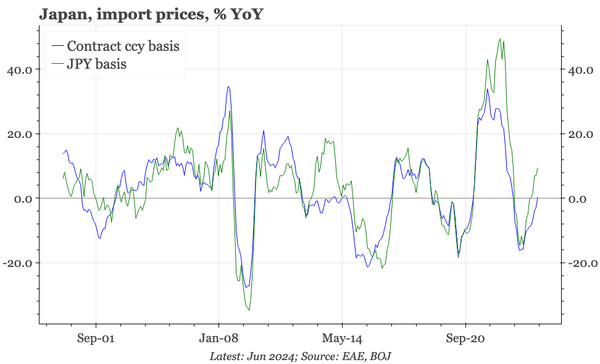
So, no surprise from the BOJ today. But the bank's statement remained constructive, revising up consumption. Today's separate services inflation data for August was also firm. Import prices have receded on the rising JPY, but we'd think the BOJ should be hiking again with a strong Q3 Tankan.
Japan – still on track
It is clear that the market moves that accompanied the BOJ's July policy changes are impacting prices. But it isn't obvious that they have derailed the underlying path for the economy. It seems to us the door remains open for an October hike, with the obvious risk being events in the US.
Japan – activity still solid
The Economy Watchers survey improved in August. That matters, as if the market vol around the BOJ meeting in July had caused damage to the cycle, it should be showing up by now. The rise in the household score is particularly important, given the previous weakness of consumption.
Japan – solid wage growth
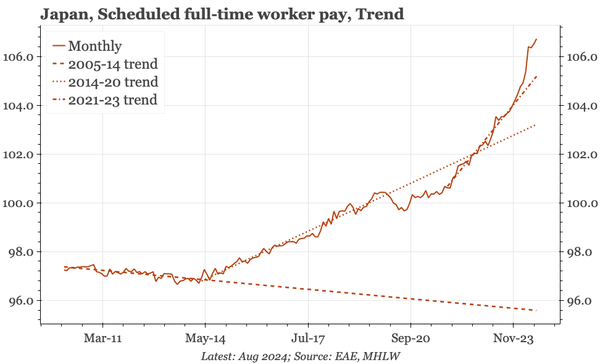
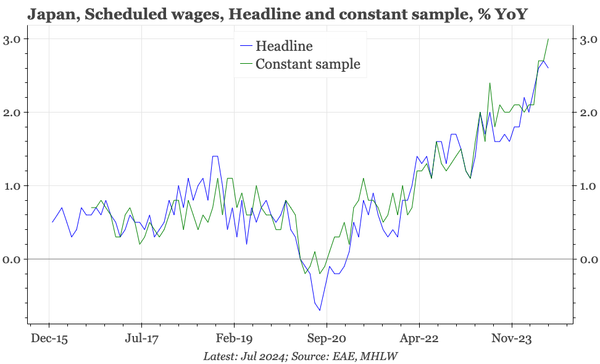
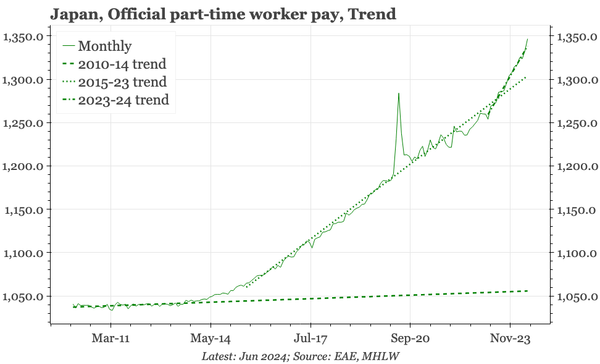
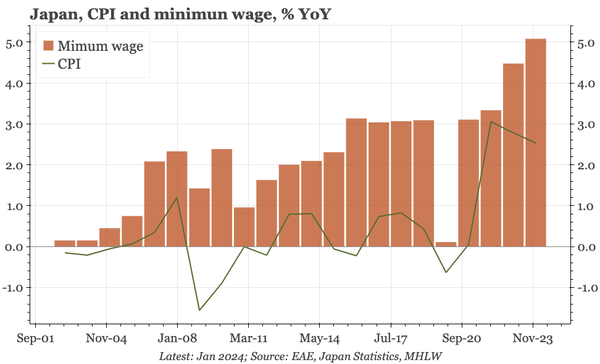
At a headline level, wages were firm in August, with the details, if anything, a bit stronger still. In particular, full-timer pay in the constant sample data rose 3% YoY, and part-time hourly wages rose 4% YoY. The wage-price cycle that was the basis for the July rate hike still looks on track.
Japan – remarkably profitable
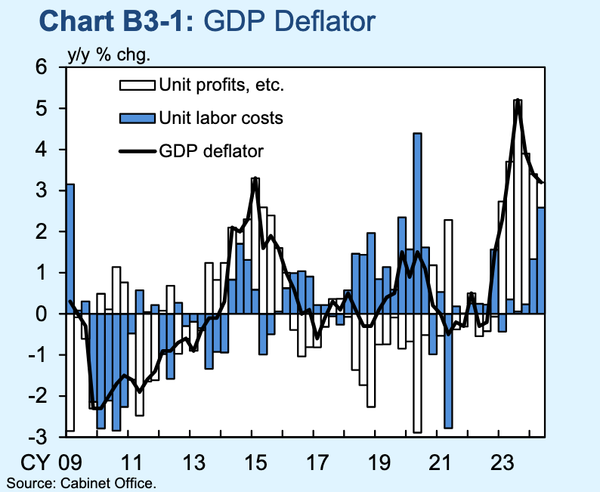
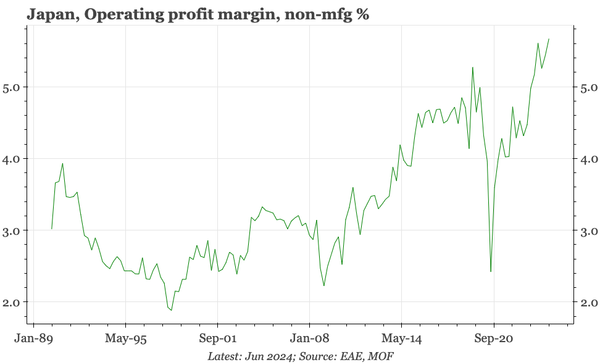
There's a lot of concern about weak profits in China. In Japan, profitability by contrast continues to get stronger, boosted in Q2 by sales and a further rise in margins. After a sharp fall in 2023, the labour share has stabilised, but with capex modest, cash holdings remain large.
Japan – inflation on track
The BOJ's Himino emphasised this week that the policy path isn't set in stone. But the bank does seem to have quite a strong view on the path the economy is taking. This week's inflation data were consistent with that, but labour market data were a bit softer, and there's no consumer pick-up yet.
Japan – services inflation still near 2%
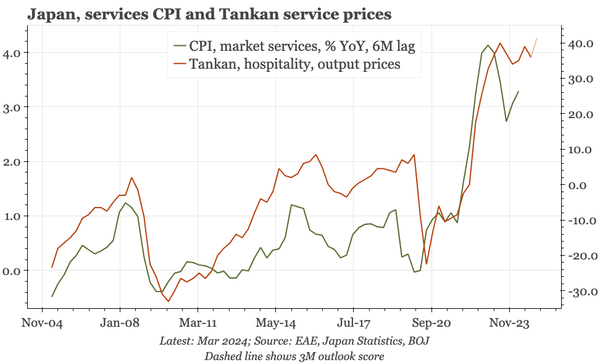
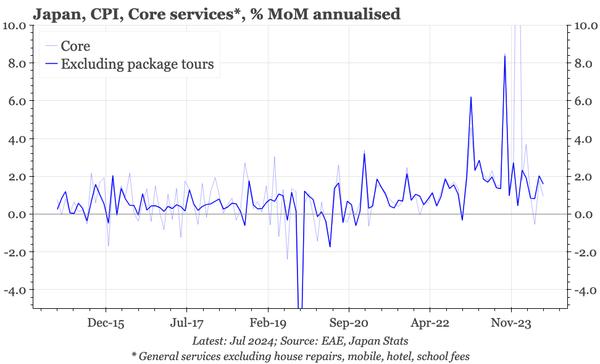
Headline measures of inflation were generally weaker in July, and JPY appreciation and energy subsidies will cause more falls in the next couple of months. To get a sense of underlying inflation, we are watching core services CPI – stable in July – services PPI, wages and the Tankan.
Japan – signs of recovery in consumption
GDP grew in Q2 for the first time in a year. The driver was domestic demand, and with nominal wage growth rising, and a greater probability that the high in $JPY has been seen, it is becoming more likely that this recovery in spending can now continue.
Japan – confident but not dogmatic
In the BOJ's first comments since last week, Uchida says that policy is dependent on the economic outlook, which could be affected by market moves, particularly the JPY. However, he also reiterates confidence in the underlying changes that the BOJ has been talking about throughout this year.
Japan – solid wage data
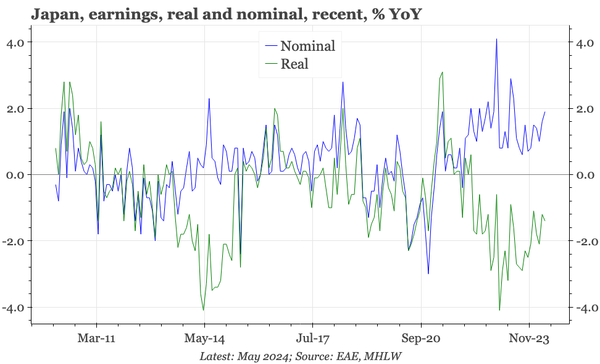
The June jump in earnings was almost all about bonuses. But the details were solid: for full-timers, wage growth didn't slow much, and it accelerated for part-timers. There's also now a greater likelihood of a trend rise in real wags as the less-weak JPY dampens import prices.
Japan – taking stock
The huge moves in markets may well have an impact on the extent and pace of further BOJ policy normalisation. But when markets settle down, developments in the real economy will also matter. It will be particularly important to track SME wages, service prices, and consumption.
Japan – confident on services prices, less so on SME wages
In its full outlook report, the BOJ sounds confident on services prices and wages at larger firms. It is less certain about wage rises at SMEs. Developments at smaller firms, and service price hikes in the traditional (but long-forgotten) price setting month of October, will be important to monitor.