Archive
East Asia Econ Paul Cavey

Korea – BOK confident

Korea – BOK confident

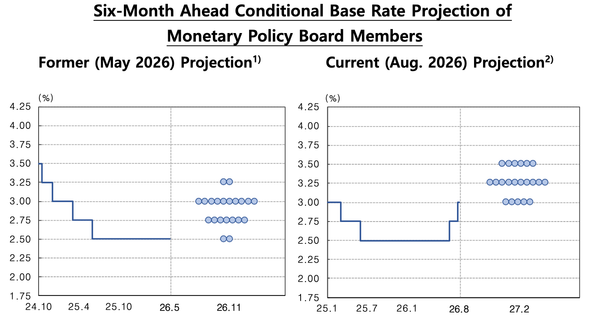
There was no change from the BOK today, and the decision to stay on hold was unanimous. That wasn't a surprise. However, the meeting was informative, with the clear takeaway being BOK confidence that this cycle will run through 2027.
3 min read

Korea – the boom that hasn't happened

Korea – the boom that hasn't happened

The BOK is unlikely to move tomorrow when it hiked twice recently, the KRW has finally firmed, and there is nervousness about the AI cycle. However, if those worries are just a wobble, then there's still much room for the semi surge to feed into domestic demand, and tomorrow will just be a pause.

6 min read

Korea – net exports v flows

Korea – net exports v flows

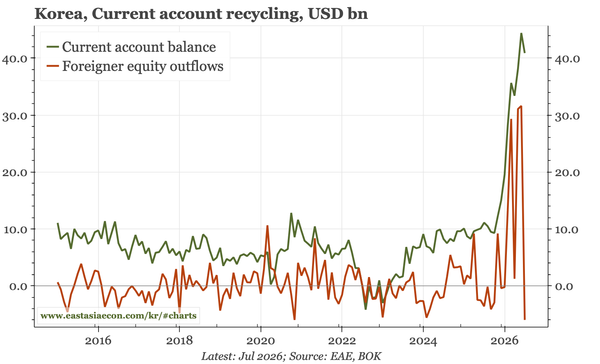
The strength of the current account in August shows Q3 will be another blowout for nominal GDP, improving all Korea's macro ratios. That provides cyclical and structural reasons for KRW strength and relative outperformance of longer-term KTBs. The headwind remains equity outflows.

3 min read

Korea – cost-push for now

Korea – cost-push for now

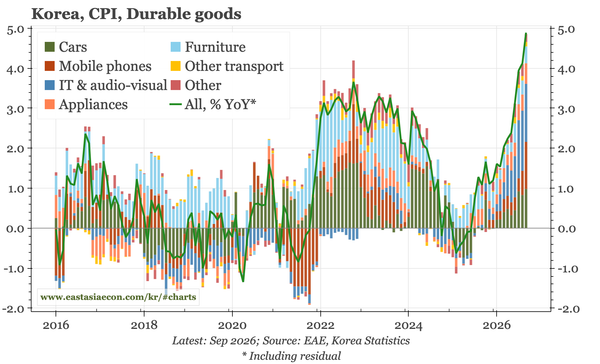
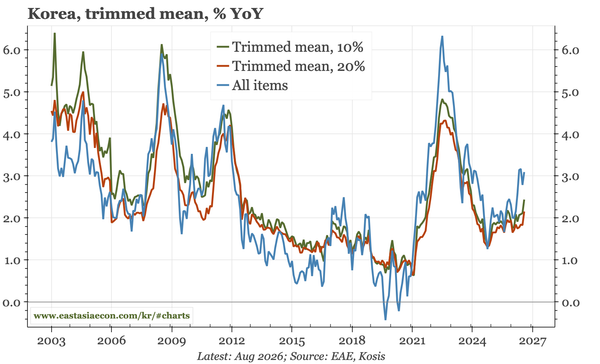
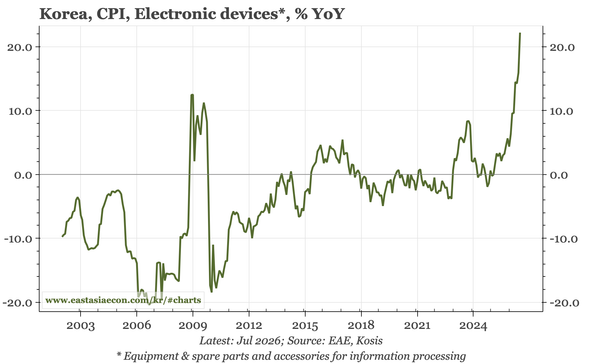
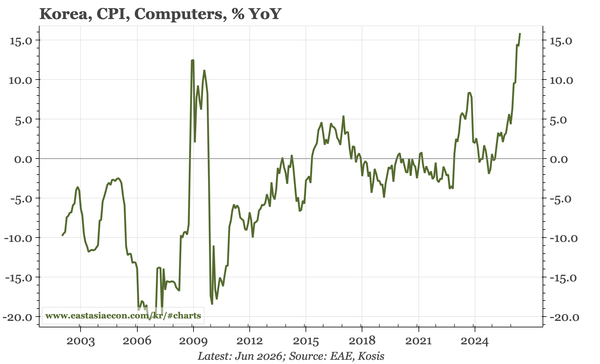
Underlying inflation was firm in September, because of energy, and the surge in semiconductor prices raising the price of electronics devices. September data show the chip shock isn't over yet, and the BOK expects demand-pull inflation to also become more obvious in the coming months.

3 min read

Korea – August a bit weaker

Korea – August a bit weaker

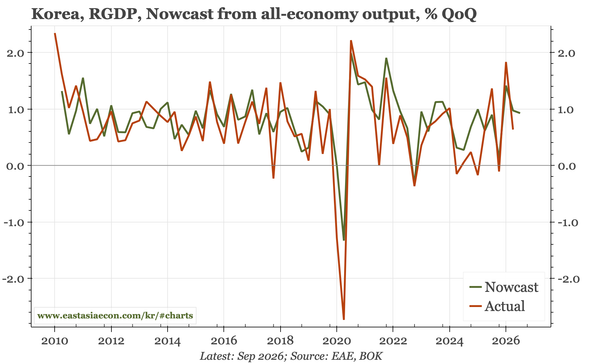
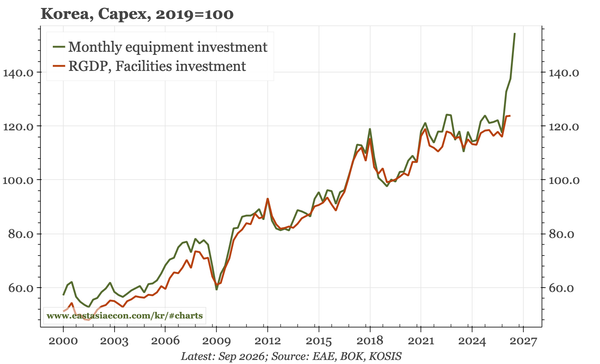
Softer output and capex in August is most likely noise, reflecting temporary issues in auto production, and lumpiness in investment spending on transport equipment. Even with that, Q3 GDP growth is tracking around 1% QoQ.

2 min read

Region – lands of fiscal plenty

Region – lands of fiscal plenty

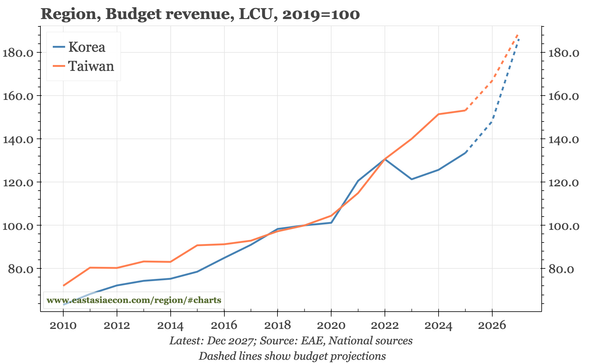
In many advanced economies, governments are drowning in debt. But in Korea and Taiwan they are floating up on the flood in revenue generated by the semiconductor boom. There is so much money that both economies plan looser fiscal policy while also paying back debt.

7 min read

Korea – the rising tide

Korea – the rising tide

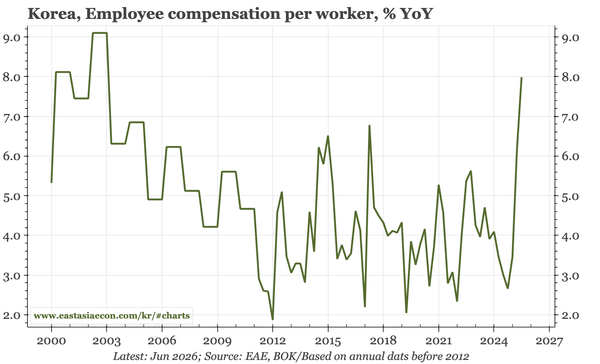
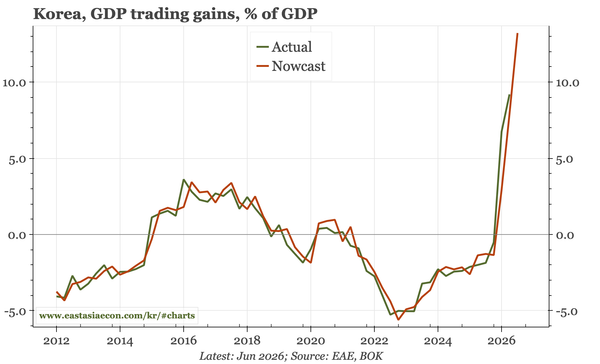
Last week's GDP data showed nominal growth of over 25% YoY in Q2. Most of that was in the form of corporate profits, but employee compensation still rose 8% YoY. With the government planning growth in fiscal spending of 12% in 2027, there are more signs of the IT sector lifting the broader economy.

4 min read

Korea – from selling to buying

Korea – from selling to buying

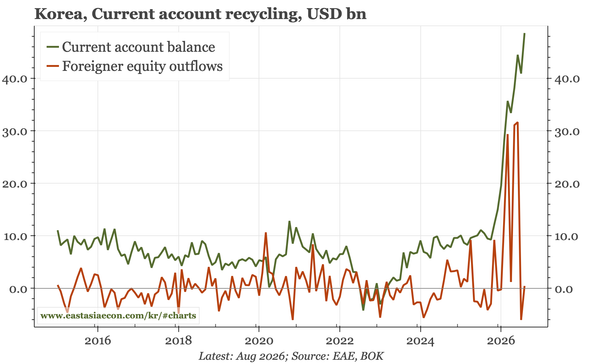
Today's BOP data show that after selling more than USD30bn of domestic equities in June, foreigners purchased USD6bn in July. That swing goes a long way to explain the sudden appreciation of the KRW. That should be able to continue, given CA surplus of over 20% of GDP, strong economy, and BOK hikes.

2 min read

Korea – inflation firm

Korea – inflation firm

I thought the underlying data in today's CPI release were firm. Despite an easing in travel expenses, core inflation (excluding mobile phone bills) remained at 2.8% YoY, the trimmed mean rose, and the diffusion across all items ticked up.

3 min read

Korea – strong July

Korea – strong July

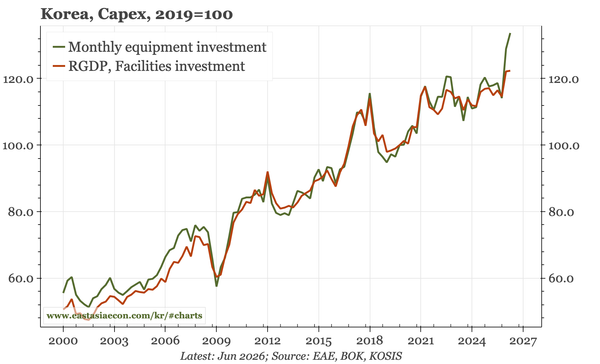
Output in July retained the gains of June, and capex spending rose further. Both suggest a strong start for GDP in Q3. Retail sales were weaker last month, but the household sector should start to benefit as the government spends the 20% growth in tax revenue of recent months.

3 min read

Korea – "pre-emptive"

Korea – "pre-emptive"

Today's BOK meeting didn't throw up any big surprises: core CPI and growth forecasts were raised against the backdrop of the TOT shock, and the bank hiked again with the aim of being "pre-emptive". However, Governor Shin's remarks at the press conference produced a lot to digest.

4 min read

Korea – still on the up

Korea – still on the up

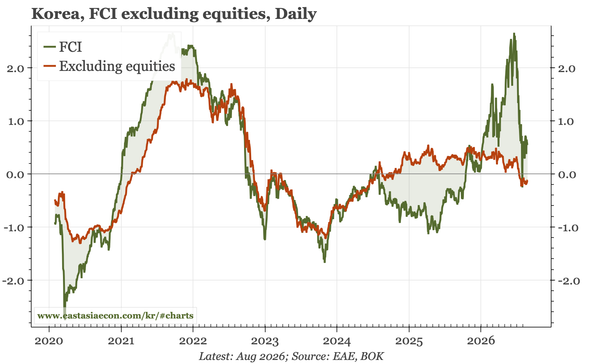
Back-to-back rate hikes aren't common, and since July, stronger KRW and lower equities have tightened FCI. However, the economic backdrop is unusually strong, so I would still expect the BOK to hike at its August meeting. That said, rather than rates, it is the KRW that looks more interesting here.

7 min read

Korea – TOT-led growth continues

Korea – TOT-led growth continues

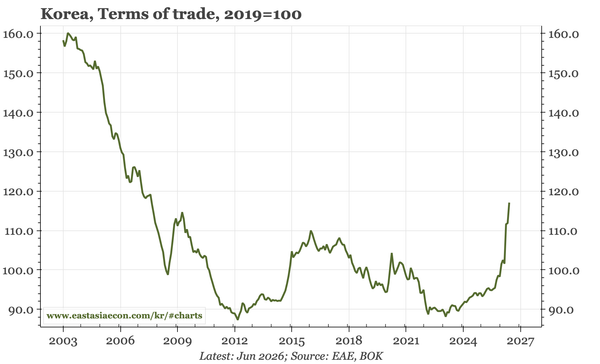
The big macro dynamic is the sharp rise in chip prices that is boosting the terms of trade, and thereby lifting nominal GDP and national income. Today's July export and import price data show that these trends remain in place. Rates have priced at least the first stage of this. The KRW still hasn't.

2 min read

Korea – the BOK's view of the TOT boom

Korea – the BOK's view of the TOT boom

The BOK this week published a nice report on spillovers from the terms of trade boom. It wouldn't be fair to say that this pays only lip service to the usual concerns on why spillovers might be limited. But the report's central expectation is that the impact will be "both sizable and persistent"

5 min read

Korea – cost-push more than demand-pull

Korea – cost-push more than demand-pull

The BOK expects core inflation to be pushed up by the chip boom, via both cost-push for electronic devices and demand-pull from the big boost to national incomes. In today's July data, the cost-push element is more obvious, though there are some tentative signs of demand-pull appearing.

2 min read

Korea – strong data in June

Korea – strong data in June

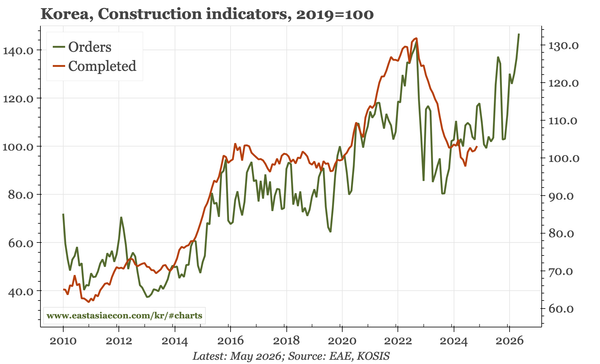
But output growth and capex were strong in June. Output was lifted by both goods and services, while the tech sector gave a boost to capex. Retail sales and construction orders were weak, but overall, the data signal a bit of upside risk for the next release of Q2 GDP data in September.

2 min read

Korea – a bit less K-shaped

Korea – a bit less K-shaped

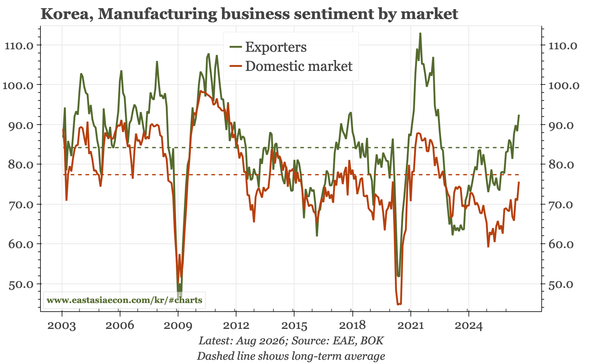
In manufacturing, sentiment is rising for both exporters and domestic firms, and capex intentions are strengthening too. That suggests support for the cycle not apparent in recent equity market moves. However, non-manufacturing sentiment is weak, and the labour market still isn't recovering.

2 min read

Korea – nominal growth nears 20%

Korea – nominal growth nears 20%

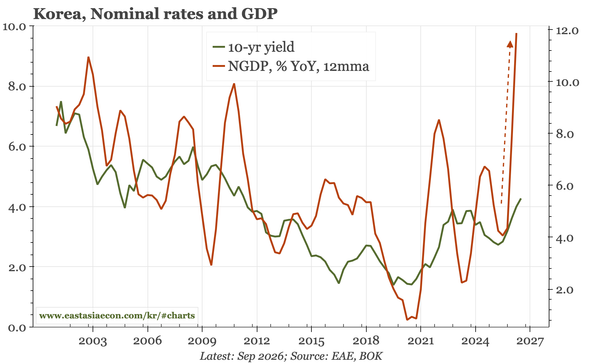
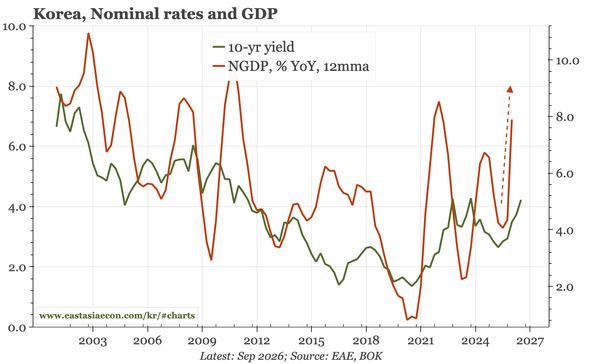
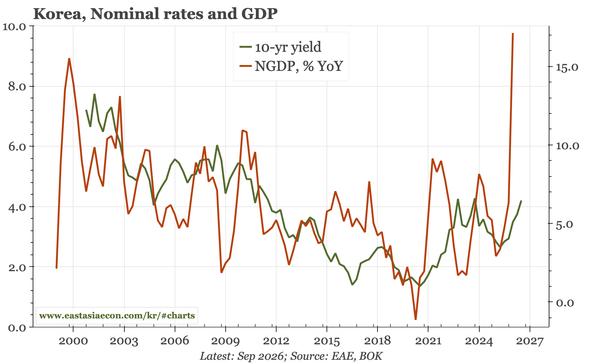
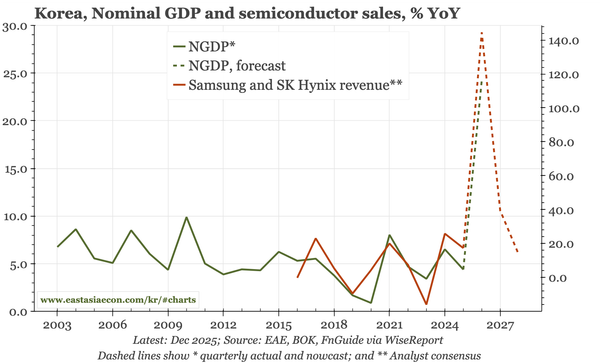
Korea's real GDP growth in Q1 was solid, but nominal continues to be spectacular, rising almost 20% YoY for the first time in 30 years. Stronger nominal growth is typical of a commodity boom, and suggests more upside for rates than implied by inflation and real GDP alone.

3 min read

Korea – mixed loan demand, firm PPI

Korea – mixed loan demand, firm PPI

In the Q3 loan officer survey, lower mortgage demand was offset by higher demand for other household loans. That points to the continuing risk of lending to finance stock purchases. The impact of the surge in equity market activity can also be seen in today's June PPI report.

3 min read

Korea – BOK more hawkish

Korea – BOK more hawkish

As expected, the BOK hiked rates by 25bp today. The bank expects 2026 GDP growth to be "considerably" higher than the previous forecast of 2.6%, partly because it expects the cycle to broaden into domestic demand. That will in turn support inflation. Relative to market pricing, that feels hawkish.

2 min read

Korea – rates to rise, but how hawkish?

Korea – rates to rise, but how hawkish?

The BOK discussion tomorrow should have two levels, the usual analysis of growth, CPI, housing, and the KRW, but also analysis of how the huge semi terms of trade shock affects medium-term economic prospects. The first justifies rate hikes. I think the second argues for more hawkishness still.

6 min read

Korea – CA surplus of 20% of GDP still doesn't matter

Korea – CA surplus of 20% of GDP still doesn't matter

The flow story behind KRW weakness has transitioned from overseas buying by domestic retail to domestic selling by foreigners. Two other factors help inform the exchange rate: correlation with the JPY and, perhaps, a BOK that is late in hiking given the huge acceleration in NGDP growth.

2 min read

Korea – transition time for CPI

Korea – transition time for CPI

The sharp rise in inflation since March slowed in June, and the BOK expects a drop in July. But cost-push from the surge in semi prices is feeding into CPI, and the BOK also expects "expanding demand pressures" from the economic recovery to drive inflation from here.

2 min read

Korea – broader cycle, but mixed

Korea – broader cycle, but mixed

There are signs of a broadening of the cycle, with construction past the worst, capex rising, and the labour market bottoming. However, while services activity has been strong recently, retail sales are still sluggish, and industrial production is going sideways.

2 min read

Korea – not quite K-shaped

Korea – not quite K-shaped

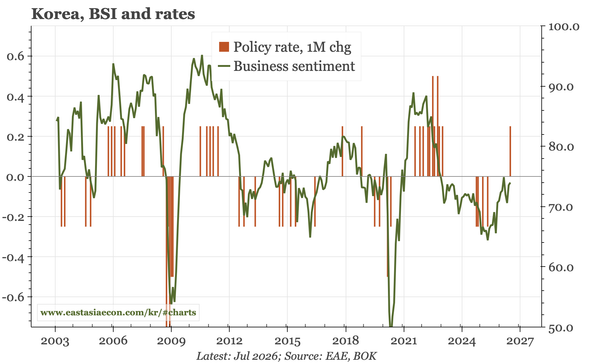
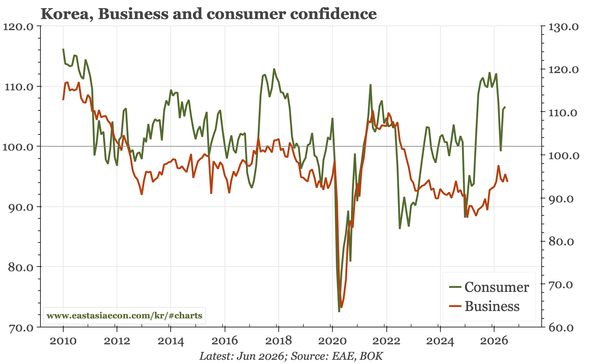
Business sentiment is middling, and the gap between large and small firms looks K-shaped. However, consumer confidence is quite strong, and the BOK has argued that sector disparities aren't an issue for monetary policy. Falling oil prices do lessen inflation risk, but also boost GDP growth.

2 min read