
Subscribers Only

Korea – BOK confident
There was no change from the BOK today, and the decision to stay on hold was unanimous. That wasn't a surprise. However, the meeting was informative, with the clear takeaway being BOK confidence that this cycle will run through 2027.
Subscribers Only
Korea – the boom that hasn't happened
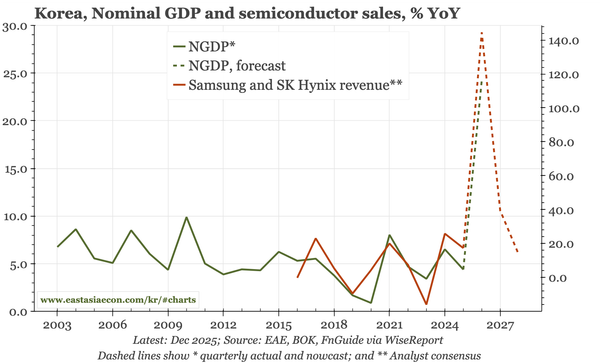
The BOK is unlikely to move tomorrow when it hiked twice recently, the KRW has finally firmed, and there is nervousness about the AI cycle. However, if those worries are just a wobble, then there's still much room for the semi surge to feed into domestic demand, and tomorrow will just be a pause.
Subscribers Only
Korea – net exports v flows
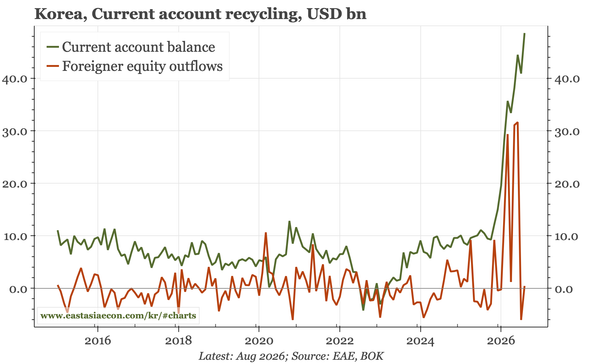
The strength of the current account in August shows Q3 will be another blowout for nominal GDP, improving all Korea's macro ratios. That provides cyclical and structural reasons for KRW strength and relative outperformance of longer-term KTBs. The headwind remains equity outflows.
Subscribers Only
Korea – cost-push for now
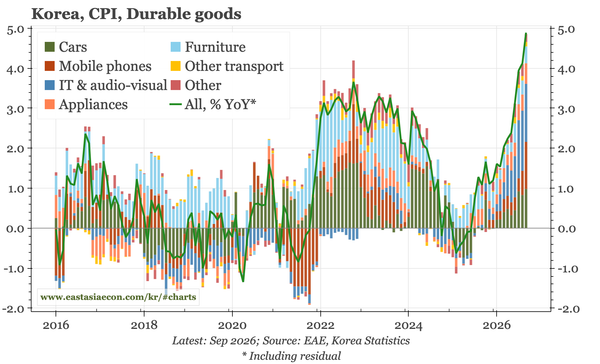
Underlying inflation was firm in September, because of energy, and the surge in semiconductor prices raising the price of electronics devices. September data show the chip shock isn't over yet, and the BOK expects demand-pull inflation to also become more obvious in the coming months.
Subscribers Only
Korea – August a bit weaker
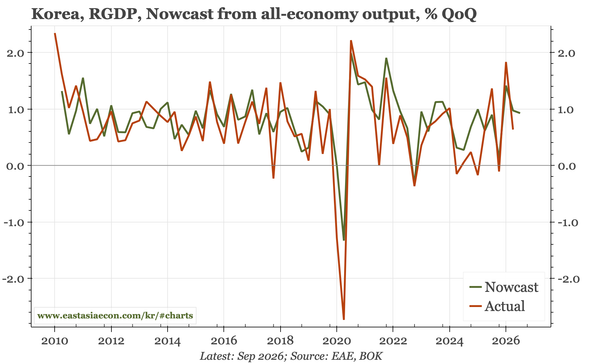
Softer output and capex in August is most likely noise, reflecting temporary issues in auto production, and lumpiness in investment spending on transport equipment. Even with that, Q3 GDP growth is tracking around 1% QoQ.
Subscribers Only
Region – lands of fiscal plenty
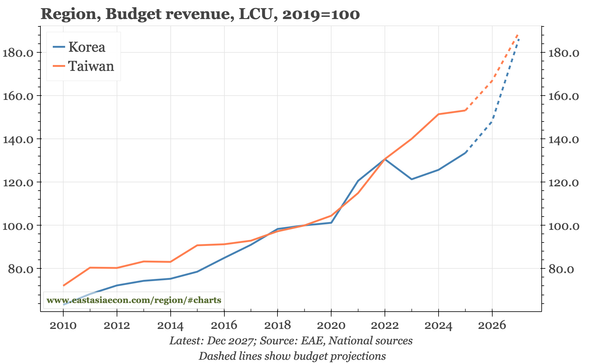
In many advanced economies, governments are drowning in debt. But in Korea and Taiwan they are floating up on the flood in revenue generated by the semiconductor boom. There is so much money that both economies plan looser fiscal policy while also paying back debt.
Subscribers Only
Korea – the rising tide
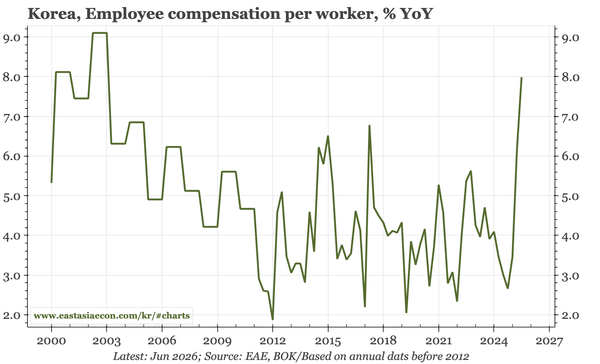
Last week's GDP data showed nominal growth of over 25% YoY in Q2. Most of that was in the form of corporate profits, but employee compensation still rose 8% YoY. With the government planning growth in fiscal spending of 12% in 2027, there are more signs of the IT sector lifting the broader economy.
Subscribers Only
Korea – from selling to buying
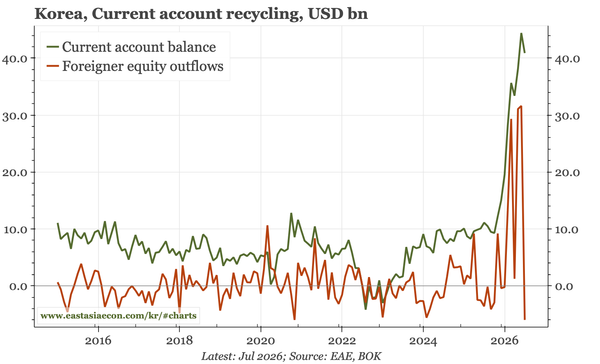
Today's BOP data show that after selling more than USD30bn of domestic equities in June, foreigners purchased USD6bn in July. That swing goes a long way to explain the sudden appreciation of the KRW. That should be able to continue, given CA surplus of over 20% of GDP, strong economy, and BOK hikes.
Subscribers Only
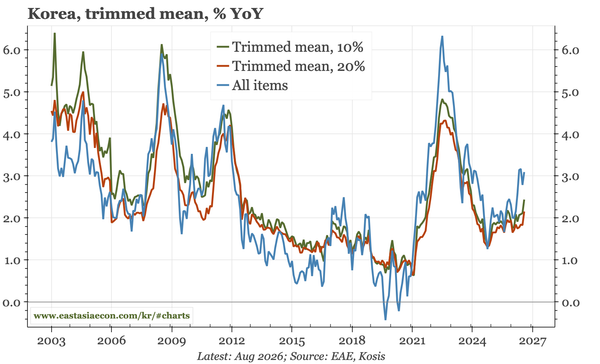
Korea – inflation firm
I thought the underlying data in today's CPI release were firm. Despite an easing in travel expenses, core inflation (excluding mobile phone bills) remained at 2.8% YoY, the trimmed mean rose, and the diffusion across all items ticked up.