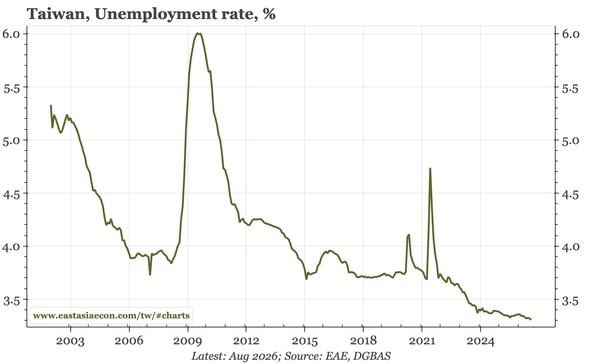
Taiwan – unemployment at 25-year low
The unemployment rate remains pinned at 25 year lows, and if anything, continues to edge down. Employment isn't changing much, but unlike Korea and Japan, nor is the participation rate. There also aren't yet clear signs that the cycle is slowing down.
Korea – AI trade continues
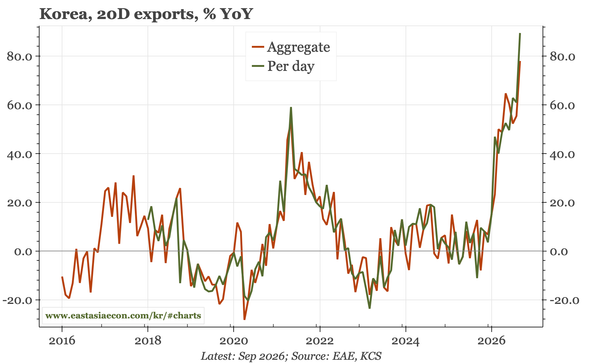
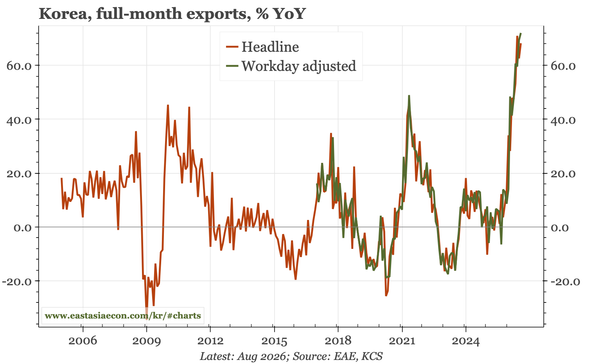
The AI-tech trade didn't end in August. Korean data for the first 20 days of September show that semiconductor exports have this month continued to rise sharply. That in turn has pushed overall export growth above 80% YoY, and likely means the trade surplus last month rose yet again.
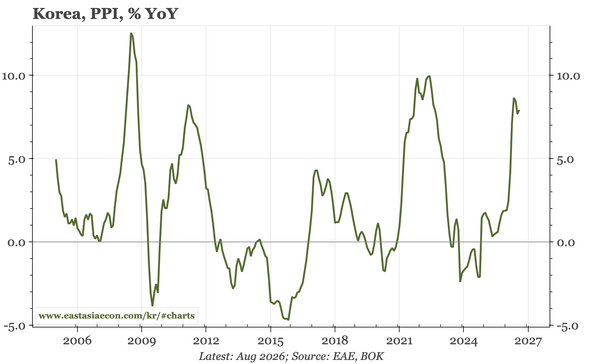
Korea – PPI ticks up
PPI inflation ticked up in August, for both goods and services. The increase in goods would have been more but for the appreciation of the KRW. However, even with the stronger currency, the rise in world oil prices through 1H September points to a further increase in upstream price pressures in…
Taiwan – property prices turn up
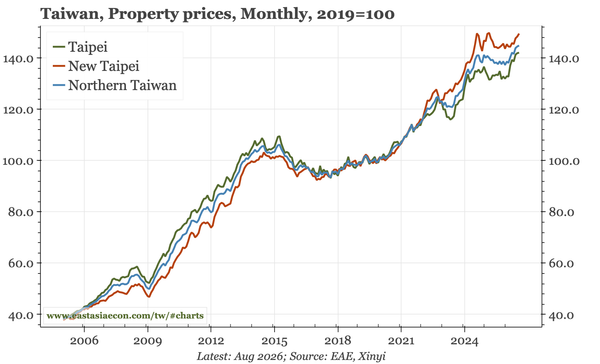
August data today from Sinyi, a real estate agent, show a continuation of the renewed upturn in property prices that began earlier this year. The monthly data only cover northern Taiwan. Quarterly data that have broader geographical coverage will be released next month.
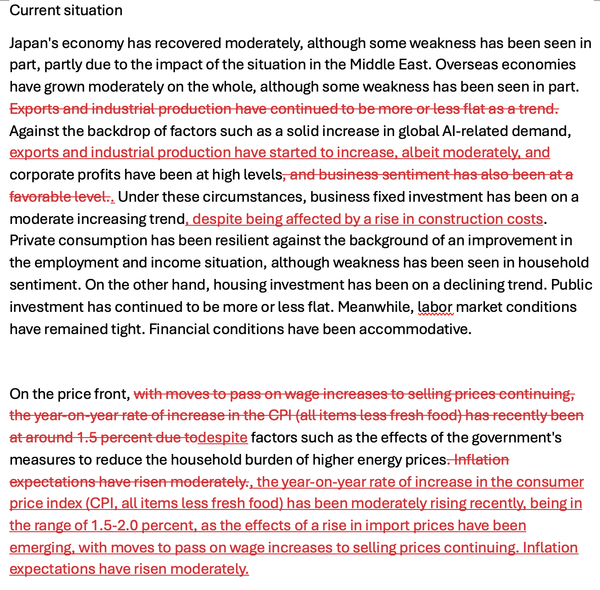
Japan – services output vs inflation
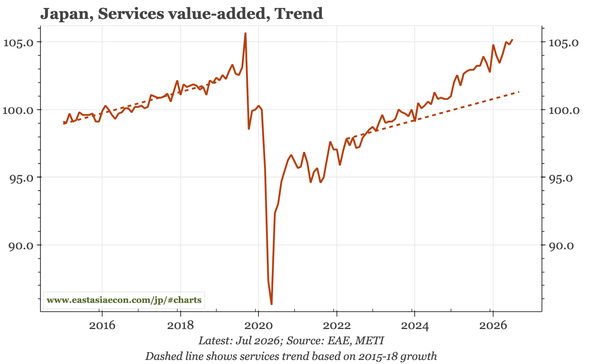
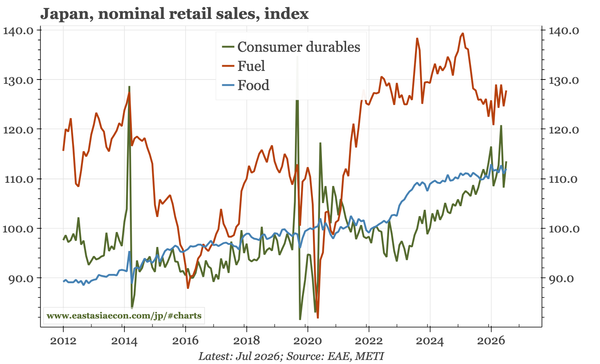
The focus of discussion around the BOJ has been inflation, and what is happening to price trends is of course important. But for me, the shift this year in growth dynamics also matters. Today's July data show that services output continues to grow at a relatively rapid rate.
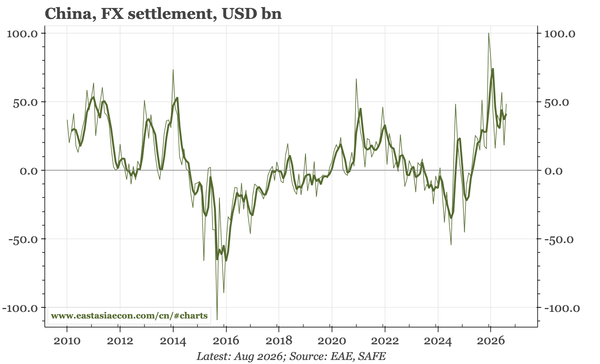
China – credit impulse declines
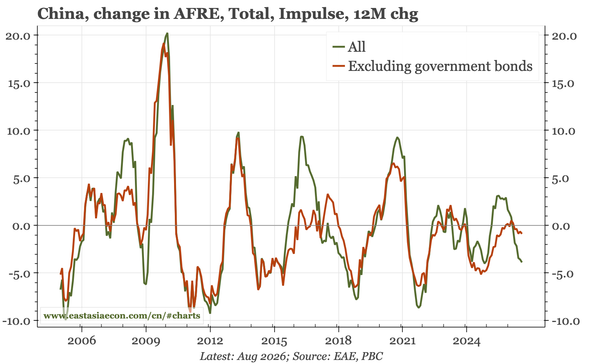
China's credit impulse continued to decline in August, but within that, there are three different sector dynamics: the drop in household lending that started in 2021 is continuing, the weakness in CGB issuance since 2025 has yet to reverse, but "other" (mainly corporate) lending is stable.
Taiwan – regular wage growth nears 3%
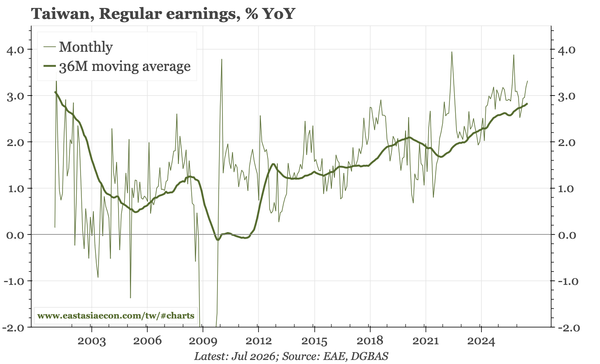
Regular wage growth was strong enough in July to lift the long-run average another step closer to 3% YoY. The renewed strength of exports in August and the rise in IP point to manufacturing continuing to be the leading sector, and consistent with that, overtime hours worked in the sector continues…
China – industrial prices rebound
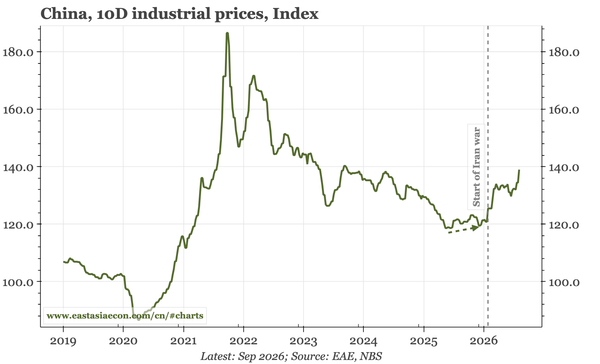
I'd thought that the rise in inflation of 1H26 was all over, but now I am not so sure. Industrial prices rebounded through August. The rise is led by energy (oil, and also coal), but is quite broad-based, with metals and even building materials prices also ticking up.
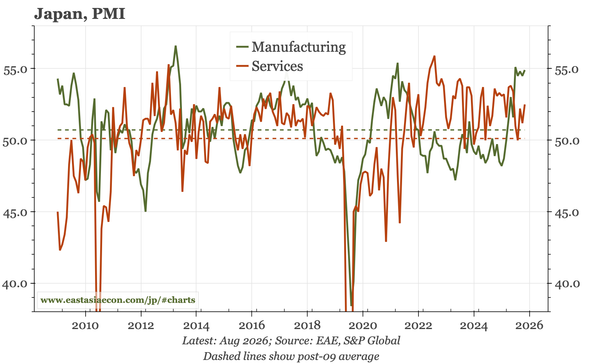
Japan – services catching up with manufacturing
In terms of sectors, the strength in Japan's cycle this year has been concentrated in manufacturing. However, after falling with the onset of the Iran war, services momentum has recovered, and while still off the highs, does suggest that activity is solid.
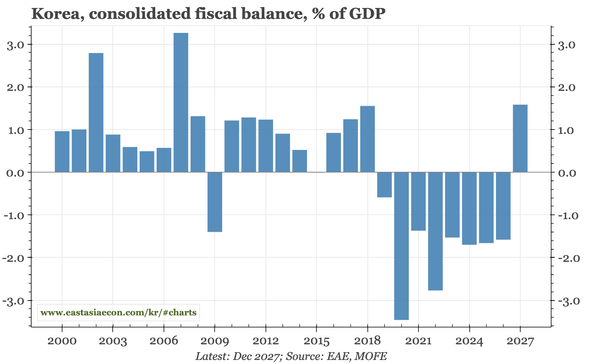
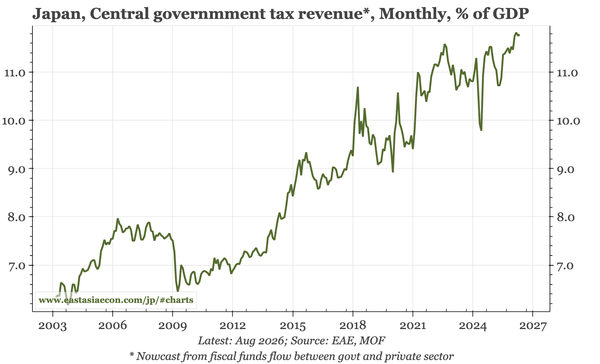
Japan – fiscal revenue trend intact
In today's data, fiscal revenue in August was perhaps a little weaker, but the trend rise of recent years remains intact. With the BOJ continuing with QT – a dynamic that is also relevant for Japan's fiscal position – the sharp contraction in the monetary base is continuing.
Taiwan – manufacturing PMI above 60
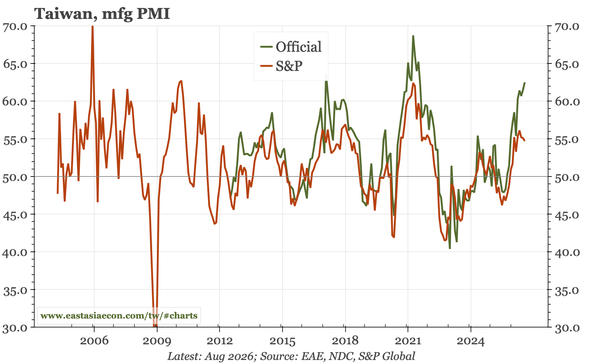
Taiwan's official manufacturing PMI rose further in August, and is now comfortably above 60. With the TWD not following the KRW stronger, input price pressures in Taiwan also ticked up again in August. The non-manufacturing PMI did soften last month.