Paul Cavey

Paul Cavey

China – px firm, construction not

China – px firm, construction not

Headline official PMIs continue to closely hug the 50 threshold. I am not sure that tells us much about the economy. But two components of the PMI are useful. The ongoing slump in construction indicates no property revival. Price indicators show PPI still strong, but warn of some weakening in CPI.

2 min read

East Asia Today

East Asia Today

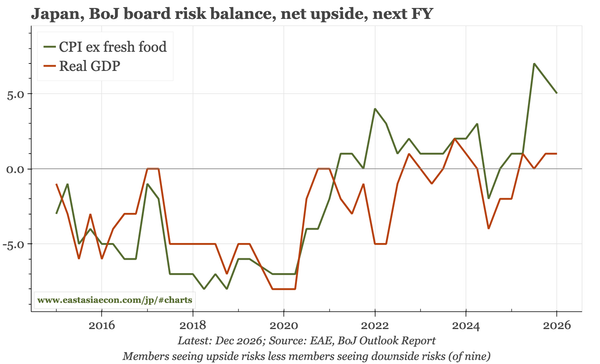
The BOJ said today that risks for overall inflation are still on the upside. Korea's month-end data releases were strong for activity and capex, weaker for consumption. Taiwan's economy re-accelerated in Q3. It is plausible that the export contribution to GDP in China rose in Q3.

3 min read

Taiwan – growth re-accelerates

Taiwan – growth re-accelerates

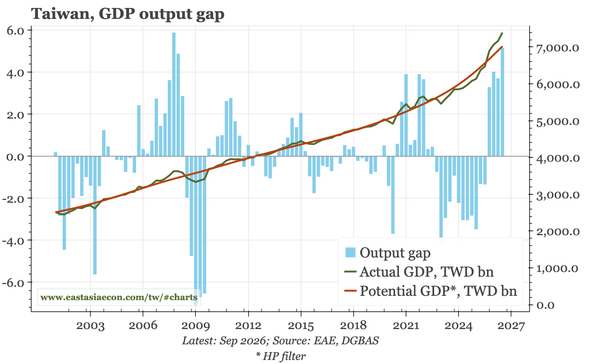
Rather than slowing as the government had forecast just a couple of months ago, GDP growth re-accelerated in Q3 to 14.4% YoY. That was because of domestic demand rather than net exports, and while that was mostly capex, consumption is growing more than 5%, and the positive output gap widened.

2 min read

Japan – 2%...but no more?

Japan – 2%...but no more?

The BOJ argues today not just that "underlying inflation" has reached 2%, but that it is expected to stay there. However, it seems clear that stability won't be achieved without some help, as its analysis also says that all the risks to prices are to the upside.

3 min read

Korea – strong, but still unbalanced

Korea – strong, but still unbalanced

Earnings releases and September macro data show the cycle has strong momentum. Growth is dominated by semis, and so dependent on the global cycle. However, the doubling in tax revenue in September shows one way in which the benefits of the semi cycle can start to broaden out.

4 min read

East Asia Today

East Asia Today

Highlights of a longer note that takes stock of Japan before the BOJ meeting tomorrow, with the theme being short-term nominal strength. In China by contrast, equity market falls highlights deflationary risk. Business sentiment in Korea ticked up. Taiwan's monitoring index in September was strong.

3 min read

Japan – medium-term concerns

Japan – medium-term concerns

With both growth and inflation strengthening, it will be tough for the BOJ not to hike faster – whatever Takaichi thinks. However, back-to-back or 50bp moves are unlikely. Moreover, the peaking of property prices and sluggishness in some wage indicators point to MT headwinds.

8 min read

East Asia Today

East Asia Today

Foreign equity holdings are another example of the huge impact of the AI cycle in Korea and Taiwan. Trade volume data in China illustrate again that imports are as weak as exports are strong. Money supply and credit data in Taiwan are strong, but likely not strong enough to push the CBC into action.

2 min read

Taiwan – strong, but no trigger

Taiwan – strong, but no trigger

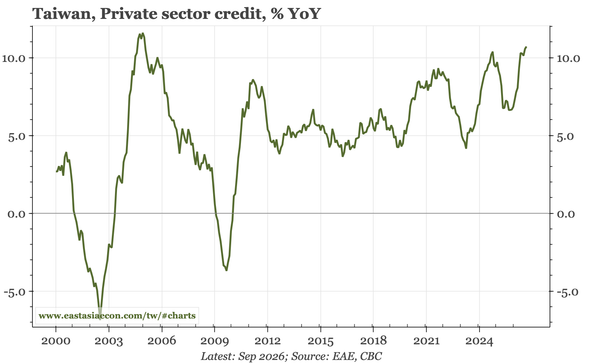
September money and credit data for September are like other indicators for Taiwan: quite strong, but not high enough on their own to think that they suddenly break the CBC's apparently strong desire not to change policy.

2 min read

East Asia Today

East Asia Today

The main data event today was Q3 GDP in Korea. In addition, China released profits data for September. There were two inflation updates in Japan, with the BOJ's measures of underlying CPI as well as services PPI. In Taiwan, we had consumer confidence for October.

3 min read

Korea – still the income tailwind

Korea – still the income tailwind

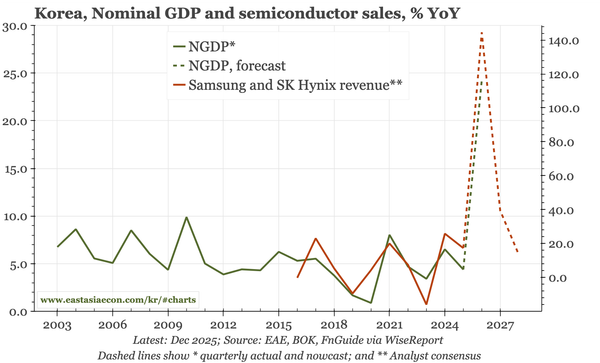
Today's Q3 GDP data continue the same story: real growth is solid, but more importantly, the huge windfall income gain from the surge in semiconductor prices remains a major tailwind for growth in 2027. The question remains how much of that income windfall will be spent.

4 min read

East Asia Today

East Asia Today

CPB's trade volume data show China's exports remaining strong, but imports flat-lining. Domestically, the second round of upstream price pressure in China since the start of the Iran War has lost momentum. That, however, is because of coal rather than oil prices.

2 min read

East Asia in Four Charts

East Asia in Four Charts

Highlights of last week's indicators: the fall in the consumption share of GDP in China; why JPY depreciation hasn't boosted Japan's export volumes; the prospects for another double-digit rise in nominal GDP in Korea in 2027; and how wage growth in Taiwan is leading the region.

2 min read

Last week, next week

Last week, next week

The sustainability of the AI cycle is critical for the region. If it ends, rates will likely be lower, but currencies not necessarily weaker. Otherwise, my themes are: China – tougher 2027; Japan – flatter curve; Korea – macro spillover; Taiwan – market spillover.

7 min read